Full Report
The numbers behind Copart, Inc.: as-reported financial statements and company metrics for FY2021–FY2025, traced to the source filings, opened with the share-price history those statements have to justify. Every linked figure opens the exact page of the filing it was printed on, with the statement row highlighted. Amounts in US$ millions unless noted.
Reading notes: All figures shown in US$ millions; filings are printed in thousands (balance sheets and income/cash-flow statements state '(in thousands)'). Values are the printed thousands rescaled to millions; each citation's anchor is the figure exactly as printed (in thousands). Main-year columns: FY2023–FY2025 income, cash-flow and revenue-disaggregation figures are from the FY2025 Form 10-K (FY2024 and FY2023 as its comparative columns); FY2021–FY2022 from the FY2023 Form 10-K. Balance sheet: FY2024–FY2025 from the FY2025 10-K, FY2022–FY2023 from the FY2023 10-K, FY2021 from the FY2021 10-K. Income-statement expense label: 'Yard operations' (FY2021–FY2024 filings) was renamed 'Facility operations' beginning with the FY2025 10-K; amounts are unchanged (e.g. FY2023 = 1,518,029 under both labels). The row is labeled 'Facility operations'; FY2021–FY2022 quotes show the original 'Yard operations' text. Beginning in the FY2024 10-K, Copart reports a redeemable noncontrolling interest: FY2024–FY2025 'Net income' (before NCI) differs slightly from 'Net income attributable to Copart, Inc.' (FY2025: 1,548,363 vs 1,552,449). The income-statement bottom line and long-term record use net income attributable to Copart, which matches reported EPS.
Share Price — Full Available History — 32 Years
The stock closed at $29.12 on Jul 31, 2026 — up 1,834,953% over the window shown (+35.4% a year), trading between $0.00 and $63.84. At that close the stock trades at 18× FY2025 diluted EPS as reported below.
Source: market price feed, monthly closes, sampled from 8,148 source observations, Mar 1994–Jul 2026. Price return only, excludes dividends. Prices are split-adjusted (1:2 on Jan 29, 1999; 1:2 on Jan 25, 2000; ×1.5 on Jan 22, 2002; 1:2 on Mar 29, 2012; 1:2 on Apr 11, 2017; 1:2 on Nov 04, 2022; 1:2 on Aug 22, 2023).
Market capitalization $28.5bn.
Market cap = 977.6M shares outstanding × the Jul 31, 2026 close of $29.12. Market-derived, shown without filing links.
FY2025 at a Glance
Revenue (US$ millions)
Operating income (US$ millions)
Net income (US$ millions)
Diluted EPS
Source: FY2025 consolidated statements [1] [2]. Click any linked figure to open the filing page with the row highlighted.
Revenue by Product and Geography
| Revenue by Product and Geography | FY2021 | FY2022 | FY2023 | FY2024 | FY2025 |
|---|---|---|---|---|---|
| United States service revenues | 2,018 | 2,533 | 2,842 | 3,126 | 3,452 |
| International service revenues | 274 | 320 | 356 | 435 | 517 |
| Total service revenues | 2,292 | 2,853 | 3,198 | 3,561 | 3,969 |
| United States vehicle sales | 255 | 412 | 348 | 339 | 404 |
| International vehicle sales | 146 | 236 | 323 | 337 | 275 |
| Total vehicle sales | 401 | 648 | 671 | 676 | 678 |
| Total service revenues and vehicle sales | 2,693 | 3,501 | 3,870 | 4,237 | 4,647 |
| Total service revenues and vehicle sales growth, derived | — | +30.0% | +10.5% | +9.5% | +9.7% |
Source: Disaggregation of revenue note (service revenues and vehicle sales, split United States vs. International); total from Consolidated Statements of Income [3] [1] [4] [2]. Click any linked figure to open the filing page with the row highlighted.
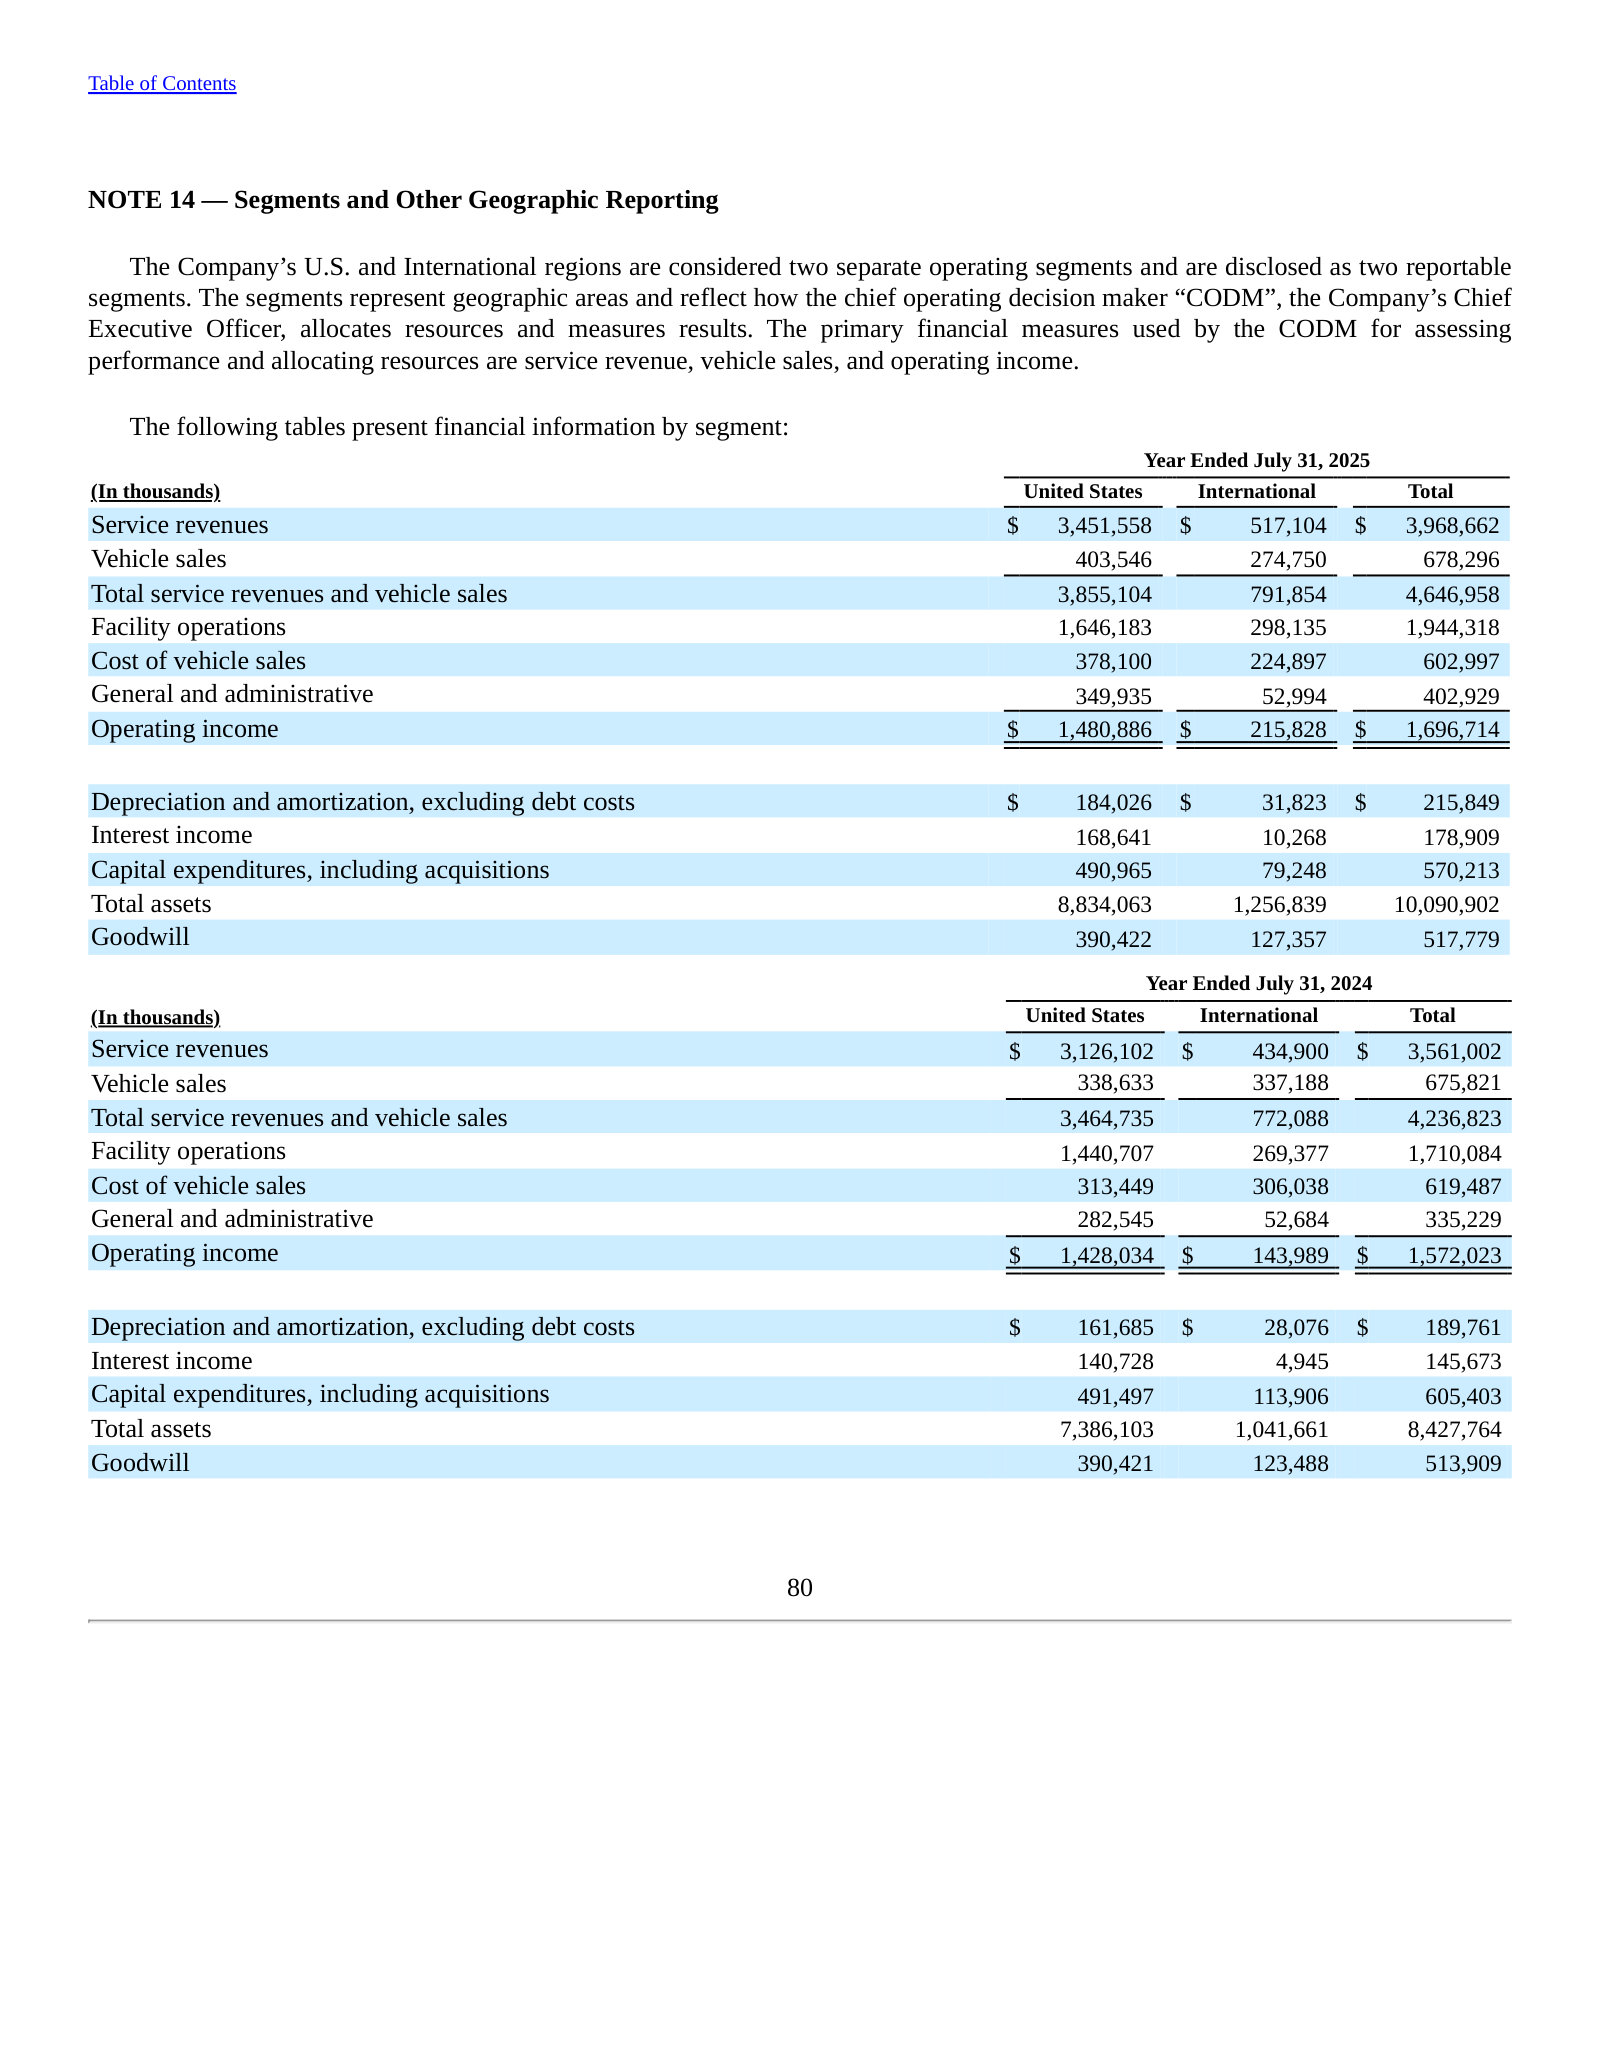
Operating Income by Segment (Geography)
| Operating Income by Segment (Geography) | FY2021 | FY2022 | FY2023 | FY2024 | FY2025 |
|---|---|---|---|---|---|
| United States operating income | 1,024 | 1,248 | 1,368 | 1,428 | 1,481 |
| International operating income | 113 | 127 | 118 | 144 | 216 |
| Total operating income | 1,136 | 1,375 | 1,487 | 1,572 | 1,697 |
Source: Note 14 — Segments and Other Geographic Reporting [5] [6]. Click any linked figure to open the filing page with the row highlighted.
Income Statement
Source: Consolidated Statements of Income [1] [2]. Click any linked figure to open the filing page with the row highlighted.
Columns marked E are consensus analyst estimates from S&P Capital IQ (CapIQ), shown alongside reported results for direct comparison; they are not company guidance.
Estimate source: S&P Capital IQ (CapIQ) consensus, as of 2026-08-03. Estimate figures are S&P Capital IQ consensus (vendor data — no filing page links). EPS and net income use the normalized (adjusted) consensus where the street reports it. Line-item analyst models (segments, drivers, KPIs) are in the Visible Alpha tab.
Balance Sheet
Source: Consolidated Balance Sheets [7] [8] [9]. Click any linked figure to open the filing page with the row highlighted.
Cash Flow
Source: Consolidated Statements of Cash Flows [10] [11]. Click any linked figure to open the filing page with the row highlighted.
Auction Marketplace Buyer Reach
| Auction Marketplace Buyer Reach | FY2021 | FY2022 | FY2023 | FY2024 | FY2025 |
|---|---|---|---|---|---|
| U.S. vehicles sold to non-local members (% of units) | 64.1% | 66.1% | 66.2% | 68.4% | 69.8% |
| — of which sold to out-of-state U.S. members (% of units) | 29.7% | 29.7% | 32.2% | 30.4% | 31.0% |
| — of which sold to International members (% of units) | 34.4% | 36.4% | 34.0% | 38.0% | 38.8% |
| Registered members ("buyers") in database | — | — | — | 1,000,000 | 1,000,000 |
Source: company filings [12] [13] [14] [15]. Click any linked figure to open the filing page with the row highlighted.
Operating Footprint Workforce
| Operating Footprint Workforce | FY2021 | FY2022 | FY2023 | FY2024 | FY2025 |
|---|---|---|---|---|---|
| Total operating facilities globally | — | — | — | — | 281 |
| New operating facilities opened, United States | 10 | 5 | 8 | 4 | 3 |
| Full- and part-time employees | 8,600 | 9,500 | 10,200 | 11,700 | 11,600 |
Source: company filings [16] [17] [18] [19]. Click any linked figure to open the filing page with the row highlighted.
Effective Tax Rate Cash Items
| Effective Tax Rate Cash Items | FY2021 | FY2022 | FY2023 | FY2024 | FY2025 |
|---|---|---|---|---|---|
| Effective income tax rate | 16.5% | 18.7% | 20.4% | 20.5% | 18.3% |
| Income taxes paid, net of refunds | 178 | 263 | 258 | 286 | 409 |
| Interest paid | 20 | 18 | 3 | 3 | 2 |
Source: company filings [10] [20] [21] [11]. Click any linked figure to open the filing page with the row highlighted.
Long-Term Record
| Fiscal year | Total service revenues and vehicle sales | Operating income | Net income | Diluted net income per common share | Net cash provided by operating activities | Capital expenditures |
|---|---|---|---|---|---|---|
| FY2016 | 1,268 | 406 | 270 | — | — | 174 |
| FY2017 | 1,448 | 461 | 394 | — | 492 | 172 |
| FY2018 | 1,806 | 584 | 418 | — | 535 | 288 |
| FY2019 | 2,042 | 716 | 592 | — | 647 | 374 |
| FY2020 | 2,206 | 816 | 700 | — | 918 | 592 |
| FY2021 | 2,693 | 1,136 | 936 | 0.97 | 991 | 463 |
| FY2022 | 3,501 | 1,375 | 1,090 | 1.13 | 1,177 | 337 |
| FY2023 | 3,870 | 1,487 | 1,238 | 1.28 | 1,364 | 517 |
| FY2024 | 4,237 | 1,572 | 1,363 | 1.40 | 1,473 | 511 |
| FY2025 | 4,647 | 1,697 | 1,552 | 1.59 | 1,800 | 569 |
Source: consolidated statements across filings; older years from the standardized feed [10] [1] [11] [2]. Click any linked figure to open the filing page with the row highlighted.
Analyst Consensus
Mean target
Median target
High target
Low target
Street ratings: 5 strong buy, 2 buy, 5 hold, 1 sell. Consensus: Buy.
Estimate source: S&P Capital IQ (CapIQ) consensus, as of 2026-08-03. Estimate figures are S&P Capital IQ consensus (vendor data — no filing page links). EPS and net income use the normalized (adjusted) consensus where the street reports it. Line-item analyst models (segments, drivers, KPIs) are in the Visible Alpha tab.
Traceability
364 of 378 figures on this page (96%) link to the filing page where they are printed — click a linked figure to open the source PDF at that page with the row highlighted. Unlinked figures come from standardized data feeds or pre-filing years.
All figures shown in US$ millions; filings are printed in thousands (balance sheets and income/cash-flow statements state '(in thousands)'). Values are the printed thousands rescaled to millions; each citation's anchor is the figure exactly as printed (in thousands).
Main-year columns: FY2023–FY2025 income, cash-flow and revenue-disaggregation figures are from the FY2025 Form 10-K (FY2024 and FY2023 as its comparative columns); FY2021–FY2022 from the FY2023 Form 10-K. Balance sheet: FY2024–FY2025 from the FY2025 10-K, FY2022–FY2023 from the FY2023 10-K, FY2021 from the FY2021 10-K.
Income-statement expense label: 'Yard operations' (FY2021–FY2024 filings) was renamed 'Facility operations' beginning with the FY2025 10-K; amounts are unchanged (e.g. FY2023 = 1,518,029 under both labels). The row is labeled 'Facility operations'; FY2021–FY2022 quotes show the original 'Yard operations' text.
Beginning in the FY2024 10-K, Copart reports a redeemable noncontrolling interest: FY2024–FY2025 'Net income' (before NCI) differs slightly from 'Net income attributable to Copart, Inc.' (FY2025: 1,548,363 vs 1,552,449). The income-statement bottom line and long-term record use net income attributable to Copart, which matches reported EPS.
Per-share figures reflect Copart's post-split basis. The FY2021 10-K reported FY2021 diluted EPS of $3.90 on a pre-split basis; later filings restate FY2021 to $0.97 (a 4-for-1 cumulative adjustment from subsequent stock splits). Long-term diluted EPS is therefore shown only for FY2021–FY2025 (consistent post-split basis); FY2016–FY2020 per-share figures are omitted as not comparable without adjustment.
Investment in held-to-maturity securities became a balance-sheet line beginning FY2023 (year-end holdings were nil at July 31, 2021 and 2022); FY2021–FY2022 are shown blank.
FY2016–FY2018 long-term figures (and FY2016 operating cash flow, which the feed omits) are from the standardized SEC XBRL data feed and are shown without page links; FY2019–FY2020 are from the FY2021 Form 10-K comparative columns.
Copart pays no dividend and made no share repurchases in FY2020–FY2025; buybacks are therefore not shown as a cash-flow row.
1 figure(s) differed between the data feed and the filing; the filing value is shown (see the run's metrics/metrics_tab.json for the audit trail).
Copart, Inc.'s management answers for the business every quarter. These are the exchanges that explain it best — verbatim, from the call transcripts preserved in Sources. Each link opens the full transcript at that page in a new tab.
Q3 FY2026 Earnings Call — Q3 FY2026
The most recent call and the clearest single walkthrough of how the marketplace actually works — the total-loss-frequency growth algorithm, crossover buyers, pure-sale liquidity, and the whole-car spectrum. · Open the full transcript →
The core growth algorithm — and why Copart drives total loss frequency rather than passively riding it.
Jeffrey Liaw (CEO): We believe the long-term growth algorithm for our insurance business remains very much intact, that over many years, we've observed modest gradual declines in accident frequency, which are then more than offset by increases in total loss frequency. Total loss frequency is, in turn, a function of everrising repair costs, but more importantly, the differentiated returns that Copart generates by finding the highest and best use for a car globally, which is often full restoration back to roadworthiness. […] Although we always report this metric, it sounds like we described it as an industry metric, we are very much not passive beneficiaries of an increase in total loss frequency. We have helped to drive it upwards, and we view it as our ongoing responsibility to drive ever better auction returns, which then increases the attractiveness of the total loss pathway to insurance carriers
p. 1 · Read in context →
Pure sale isn't contractual — insurers 'voted with their feet' because they can't escape the auction's liquidity.
Jash Patwa (JPMorgan); Jeffrey Liaw (CEO): It's not contractual. So our insurance carrier partners maintain the discretion to manage the auctions as they see fit. In comparison to where we were even 7 or 8 years ago, many more insurance carriers have moved to effectively a nearly 100% pure sale approach […] If you were to watch one car transact at Copart, you'll see buyers in Poland bidding against buyers in Oklahoma, Maine, Canada, Ecuador. You'll see it happen in real time. So they recognize that there is no real way to escape the liquidity at Copart. […] Buyers tend to gravitate to pure sale items. And you tend to generate better outcomes and faster outcomes when buyers are excited to participate.
p. 7 · Read in context →
Q4 FY2025 Earnings Call — Q4 FY2025
The most recent full-year call: management makes the case for the auction-liquidity moat, lays out capital-allocation discipline for a ~$4.8B cash pile, and reframes the addressable market. · Open the full transcript →
The moat in one passage — uniquely digital, uniquely global, with a deliberately fragmented buyer base.
Jeff Liaw (CEO): First, I would note that Copart's auction is uniquely digital. We have been exclusively an online auction platform since 2003, almost two decades before our competitors followed suit and only when they were compelled to do so by the COVID-19 crisis. By extension, we are also uniquely global. We have some 300,000 paying registered members at Copart from virtually every non-sanctioned country around the world. […] International members account for approximately 40% of all vehicles sold at Copart's U.S. auctions, comprising almost half of auction proceeds because international buyers generally purchase vehicles that are more valuable than those acquired by domestic buyers. […] As context, the top 10 individual buyers of vehicles at Copart collectively purchased a low single-digit percentage of all the vehicles we sell at U.S. auctions.
p. 2 · Read in context →
Why catastrophe response is a loss-leading service: Copart is 'the insurance provider for the insurance industry.'
Jeff Licht (Stephens); Jeff Liaw (CEO): Catastrophic events are surely not se profitable for Copart. It's a service offering we provide for our insurance industry. They know that we are the backstop. So we are the insurance provider, so to speak, for the insurance industry themselves. We bend over backwards and acquire land that sits idle for years until a major storm arrives, some owned trucks and employee drivers to make sure that we have the flexible capacity to address their needs at that time.
p. 9 · Read in context →
The hardest question — is salvage share tapped out? Liaw reframes the rival as the repair shop, and the market as 5x larger.
Josh Bapla (JPMorgan); Jeff Liaw (CEO): We view our opportunity and our threats much more expansively than that. […] the actual number of auction mediated vehicles that are sold in The United States per year is multiples of that. It's 5x or more of the volume that we sell per year. […] So in many respects, we compete with the repair shops. The higher the returns we generate, the more we can win the rights to resolve that claim versus the repair industry. And the lower the returns we generate, the more we lose head to head again through repair shops as well. So there are a number of competitive threats that we face on any given day.
p. 10 · Read in context →
Q1 FY2026 Earnings Call — Q1 FY2026
Management lays out a five-indicator framework for measuring auction liquidity and works through the total-loss-frequency and international-buyer mechanics in unusual depth. · Open the full transcript →
Why international buyers set the price: as winner or 'push' bidder on most U.S. lots, they favor cars worth the freight.
Chris Bottiglieri (BNP Paribas); Jeff Liaw (CEO): if the institutional buyer wins the vehicle, and that speaks for approximately half of our U.S. auction value is going to an international buyer. Or they are the push bidder, they're the second high bidder, which helps to dictate the ultimate sale price of the vehicle. […] the average car bought by an international buyer is 38% more valuable than the average car bought by a domestic buyer. That is largely because, yes, they favor the higher end. You can imagine that if you are incurring the freight costs to move a car from here to Poland, it has to be worth your while, right? You're not moving a $400 vehicle that's mostly just its metal, right? That will never be worthwhile to move halfway across the world.
p. 7 · Read in context →
Q4 FY2022 Earnings Call — Q4 FY2022
The landmark strategy primer: Liaw sets aside the quarter to state Copart's durable operating beliefs — owning land in perpetuity, ambivalence to used-car prices, episodic buybacks — and fields a sharp market-share/antitrust challenge. · Open the full transcript →
The four durable operating beliefs that guide every decision, stated in place of the usual quarterly recap.
Jeffrey Liaw (President & Co-CEO): we'll focus our prepared remarks on a more durable operating beliefs and principles that guide our decision-making, namely that we will, one, invest in our physical infrastructure, technology platform and customer service offerings to improve auction, liquidity, and returns for our sellers. We will collaboratively engage with our sellers, both day to day and through catastrophic events to protect them and their policyholder relationships. We will actively expand our addressable market by growing our volume of lesser damaged and whole cars from both insurance and noninsurance sellers. And finally, that will continue our expansion into international markets around the world.
p. 4 · Read in context →
The land moat: ~16,000 acres, ~90% owned 'in perpetuity,' $2B invested in five years, on a deliberately conservative balance sheet.
Jeffrey Liaw (President & Co-CEO): owning our facilities enables us to control our own destiny, ensuring the sustainability of our business for our customers. We are not just participants in our industry, we are stewards of it. Today, we operate on nearly 16,000 acres of land worldwide and own approximately 90% of it, controlling it in perpetuity. Over the last five years alone, we've invested nearly $2 billion in land acquisition and development. Similarly, we have maintained a conservative balance sheet since our founding.
p. 6 · Read in context →
Why the post-COVID dip in total loss frequency is temporary — the 40-year trend is unambiguous.
Jeffrey Liaw (President & Co-CEO): Total loss frequency for the second calendar quarter in 2022 was approximately 16.9% in comparison to 19.7% for the same quarter a year ago. If vehicles had been totaled at the same rate as last year, we would have observed insurance industry volumes 15% higher than what we actually experienced. In simple Layman's terms, in a world in which replacement vehicles are harder to come by, total loss settlements are a less attractive resolution to an auto accident claim than they otherwise would be. While total loss frequency has declined over the past year and a half or so, the 40-year trend is unambiguous. We believe firmly that the market will revert to the historical norm of steadily rising total loss frequency in the months and years ahead.
p. 7 · Read in context →
International expansion as market conversion: turning Germany from a listing model to a liquid auction, carrier by carrier.
Bret Jordan (Jefferies); Jeffrey Liaw (President & Co-CEO): The model that we offer is a liquid auction as opposed to a listing service model that exists there today. And we're working with the insurance carriers to effectively convert the market to a different way of doing business. So it's not per se head-to-head competition against the Copart like market participants, but instead a changing of the market altogether. Today, we are selling cars on an agency basis on behalf of seven of the top 10 insurance carriers in Germany.
p. 25 · Read in context →
More calls
Q2 FY2026 Earnings Call — Q2 FY2026 · 10 pages · Go here for Liaw's clearest argument that fees matter less than total economic returns when winning consignments, plus a disciplined read on land-capacity needs and why Copart stays a 'builder' rather than an acquirer. · Open →
Q4 FY2024 Earnings Call — Q4 FY2024 · 10 pages · The fiscal-2024 annual call is the best explainer of catastrophe-response economics ('we mobilize in advance because that's what we owe our customers') and how Title Express became a share-winning moat after COVID. · Open →
Q4 FY2021 Earnings Call — Q4 FY2021 · 35 pages · Liaw's early-CEO framing of the liquidity flywheel, and the self-hedge insight that high vehicle values suppress total loss frequency — so a fall in used-car prices would lift Copart's consignment volume. · Open →
Copart, Inc.'s annual reports contain management's most considered account of the business. These are the sections, passages and visual pages worth opening in the originals preserved in Sources.
Copart, Inc. — FY2025 Annual Report (Form 10-K) — FY2025 (year ended July 31, 2025)
Latest 10-K: management's fullest account of the salvage-auction model, its insurance-seller base, unit economics, and the risks that move volume. · Open the full document →
Item 1. Business — p. 4 · Read the full section →
Defines the model: an online marketplace (VB3) selling mostly-insurance salvage as agent, with principal buying only in a few markets.
Industry Overview — p. 8 · Read the full section →
Explains the demand engine — how insurers decide total-loss vs. repair, the swing factor behind salvage supply.
When repair cost exceeds PAV less salvage value, the car is totalled — and newer, complex cars total more often.
The adjuster determines whether to pay for repairs or to classify the vehicle as a total loss based upon the adjuster’s estimate of repair costs, vehicle’s salvage value, and the PAV, as well as customer service considerations. If the cost of repair is greater than the PAV less the estimated salvage value, the insurance company generally will classify the vehicle as a total loss. […] We believe that one effect of these additional features is that newer vehicles involved in accidents are more costly to repair and, accordingly, more likely to be deemed a total loss for insurance purposes.
p. 10 · Read in context →
Item 1A. Risk Factors — Storage facility capacity — p. 33 · Read the full section →
Capacity is physical land; zoning and permits can cap growth, and catastrophe surges (Helene, Milton) can overwhelm it.
Facility capacity varies by region; hurricanes filled lots and dented results — new land is hard to permit.
Capacity at our storage facilities varies from period to period and from region to region. […] For example, Hurricanes Helene and Milton had, in certain quarters, an adverse effect on our operating results, in part because of facility capacity constraints in the impacted areas of the U.S. […] We may not be able to reach agreements to purchase independent storage facilities in markets where we have limited excess capacity, zoning restrictions or difficulties obtaining and maintaining use permits, which may limit our ability to sustain and expand our capacity through acquisitions of new land.
p. 33 · Read in context →
Item 1A. Risk Factors — Subhaulers and trucking fleet — p. 36 · Read the full section →
Every car is towed; the model leans on independent subhaulers and owned trucks, exposing it to fuel costs it may not pass on.
Reliance on independent subhaulers across 11 countries; fuel-cost increases may not be passable to sellers or buyers.
We rely primarily upon independent subhaulers to pick up and deliver vehicles to and from our storage facilities in the U.S., Canada, Brazil, the Republic of Ireland, Germany, Finland, the U.A.E., Oman, Bahrain, and Spain. […] Further, an increase in fuel cost may lead to increased prices charged by our independent subhaulers, which may significantly increase our cost. We may not be able to pass these costs on to our sellers or buyers.
p. 36 · Read in context →
Item 1A. Risk Factors — Competition and seller concentration — p. 38 · Read the full section →
The supply side is the risk: few large sellers, no long-term contracts, and dismantlers that can bypass the auction entirely.
Limited number of sellers and absence of long-term contracts leave market share exposed to competitors.
We face significant competition for the supply of salvage and other vehicles and for the buyers of those vehicles. […] Due to the limited number of vehicle sellers, particularly in the U.K., and other foreign markets, the absence of long-term contractual commitments between us and our sellers and the increasingly competitive market environment, there can be no assurance that our competitors will not gain market share at our expense.
p. 38 · Read in context →
Item 7. Management's Discussion and Analysis — p. 58 · Read the full section →
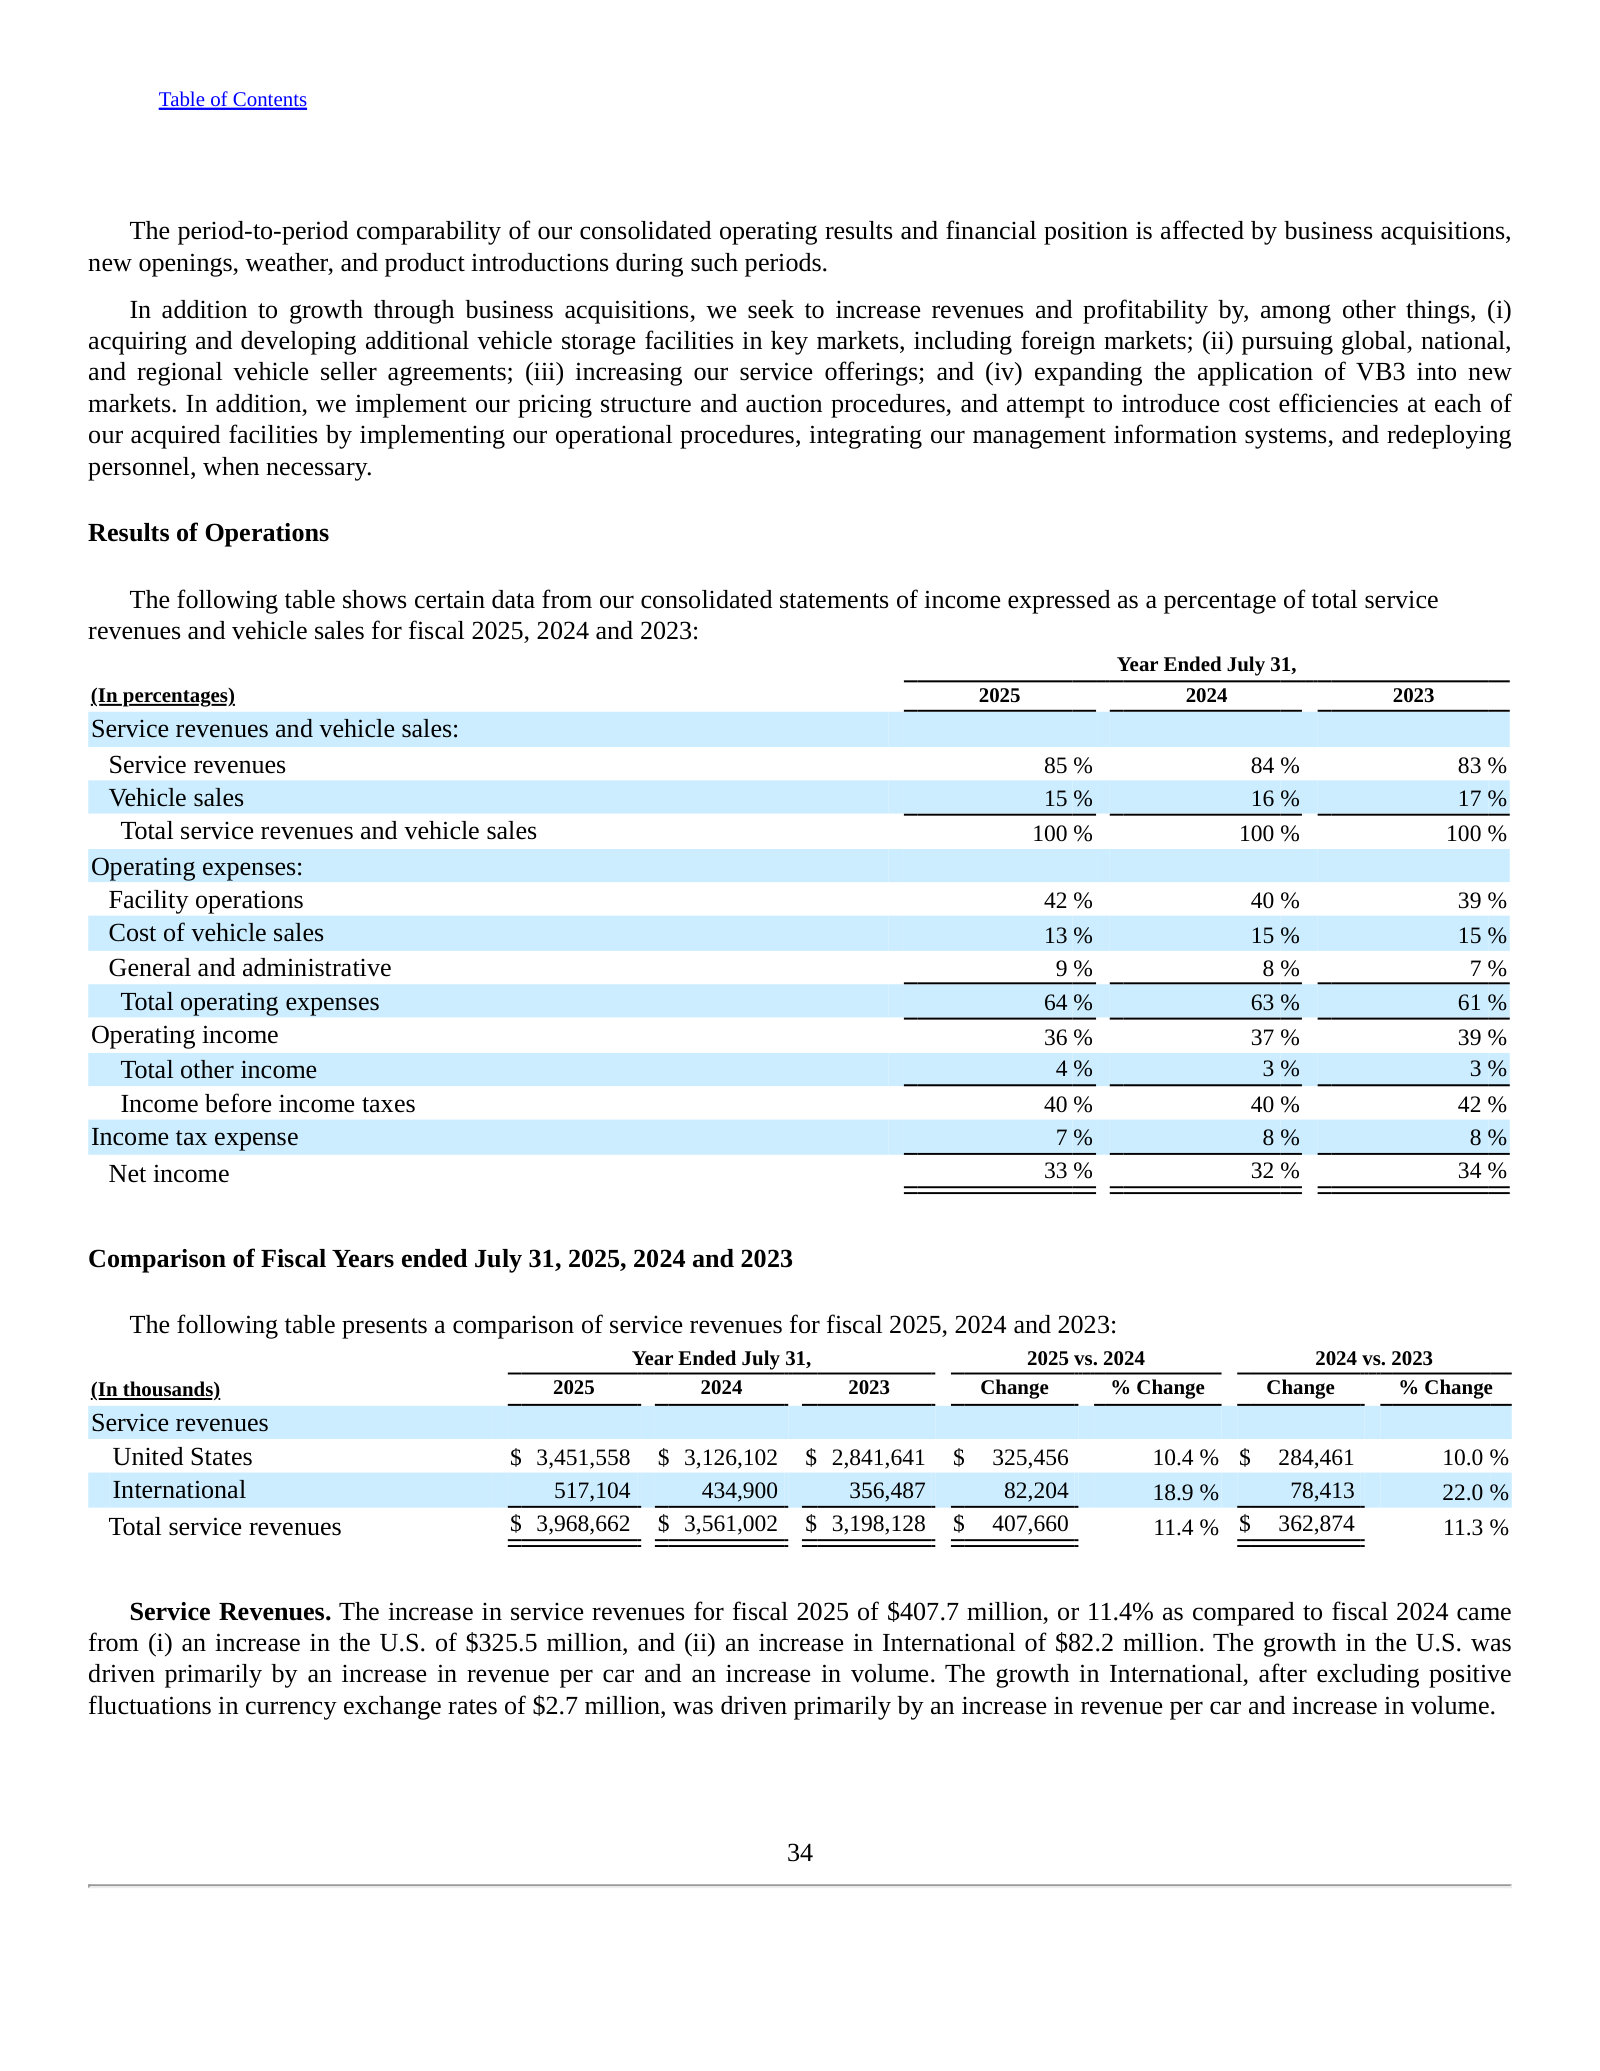
Where management explains what drives revenue and how the operating margin actually stacks up across three years.
Critical Accounting Policies — Revenue Recognition — p. 72 · Read the full section →
The accounting is the business model: consignment fees booked net (service) vs. owned cars booked gross (vehicle sales).
NOTE 14 — Segments and Other Geographic Reporting — p. 128 · Read the full section →
Two segments, U.S. and International, with the split of revenue, operating income, capex and assets that shows where the profit sits.
More annual reports
Copart, Inc. — FY2024 Annual Report (Form 10-K) — FY2024 (year ended July 31, 2024) · 129 pages · Prior year: Purple Wave acquisition and the run-up to FY2025's record revenue and margin. · Open →
Copart, Inc. — FY2023 Annual Report (Form 10-K) — FY2023 (year ended July 31, 2023) · 119 pages · Peak operating margin year (39%) — a useful baseline for the later cost-ratio drift. · Open →
Copart, Inc. — FY2022 Annual Report (Form 10-K) — FY2022 (year ended July 31, 2022) · 129 pages · Hills Motors (U.K. green-parts) acquisition and the used-car price spike that lifted salvage values. · Open →
Copart, Inc. — FY2021 Annual Report (Form 10-K) — FY2021 (year ended July 31, 2021) · 140 pages · Post-pandemic rebound edition — earliest of the five, for tracing the multi-year growth trajectory. · Open →
Competitors describe Copart, Inc.'s market in their own filings and calls. These verified passages and visual pages show where their strategies meet, using source documents preserved in Sources.
RB Global, Inc. (IAA / Insurance Auto Auctions) (RBA)
RB Global owns IAA, Insurance Auto Auctions — Copart's single most direct competitor and the #2 platform in the US insurance-salvage vehicle auction market Copart leads. IAA runs the same machine: online bidding, an international buyer base, catastrophe-surge capacity, and total-loss vehicles consigned by insurance carriers. Only the Automotive (IAA) segment is in scope here; the Ritchie Bros. heavy-equipment and commercial-truck auction business is a separate market and is excluded. The FY2024/FY2025 annual-report files indexed for RBA contain only the financial statements and notes, so the competitive narrative below is drawn from the earnings calls.
IAA's parent cites third-party CCC Intelligent Solutions data putting total-loss frequency at 24.2% — the secular driver that expands the pool of insurance-consigned vehicles feeding both IAA's and Copart's auctions — and shows how catastrophe-quarter comparisons distort headline growth (reported +3% GTV versus ~+12% ex-CAT). The 24.2% figure is an external estimate; the CAT-adjusted growth is management's own calculation.
Eric Guerin, CFO, prepared remarks (Q4 2025 earnings call): Automotive GTV increased 3% in the quarter, driven by a 2% rise in unit volumes. Excluding the impact of catastrophic activity in the fourth quarter of 2024, GTV and unit volumes grew approximately 12% and 8%, respectively. […] Throughout 2025, the inflation differential between automotive repair costs and used vehicle pricing continued to narrow, though it remained positive in the fourth quarter. This dynamic continues to support an increase in the total loss ratio, with CCC Intelligent Solutions estimating that the total loss frequency across all categories increased by 10 basis points to 24.2% compared to the prior year period. It is important to note that last year's ratio was elevated due to various catastrophic events, making the year-over-year comparison more challenging.
p. 2 · Read in context →
Asked how exposed IAA is to the troubled higher-value used-car and subprime ecosystem, the CEO scopes IAA's book as principally salvage plus a 'slightly damaged' whole-car adjunct under roughly $5,000, disclaiming exposure above $15,000. Useful for gauging how directly IAA overlaps Copart's salvage core versus Copart's own whole-car and wholesale ambitions. This is management's characterization of its mix, not independently measured.
James Kessler, CEO, Q&A response to Craig Kennison, Baird (Q3 2025 earnings call): Just as a reminder, when we talk about our whole car business, again, think about cars that are whole cars but are slightly damaged. It's very complementary to the salvage business and the buyer base that we have. And we're not really upstream in cars over a significant dollar amount like $15,000 and above. So we really have no exposure. We're really more into cars that I would call whole cars but slightly damaged is the majority of where we play. So think about a car that's less than $5,000 in that range.
p. 6 · Read in context →
IAA management asserts a fifth straight quarter of unit-volume outperformance and a 2026 net-share-gain goal in insurance salvage, while conceding a 'competitive market' — the arena Copart leads. The share-gain and ~10% ASP claims are the peer's assertions; note that unit growth was only 1% and the ASP figure reflects pricing and vehicle mix, not necessarily share.
James Kessler, CEO, prepared remarks (Q1 2026 earnings call): Despite these headwinds, gross returns measured as the salvage values as a percentage of pre-accident cash value continue to expand, supporting approximately 10% year-over-year growth in U.S. insurance Average Selling Prices. […] Unit volumes increased 1% year-over-year, marking the fifth consecutive quarter of outperformance relative to the broader market. […] We remain confident in our goal of delivering net market-share gains in 2026, as our focus on driving tangible P&L value for our partners continues to resonate and differentiate our platform. Importantly, in a competitive market, we will remain selective in pursuing volumes.
p. 1 · Read in context →
OPENLANE, Inc. (formerly KAR Auction Services) (KAR)
OPENLANE is the largest pure-play digital wholesale used-vehicle marketplace in North America and Europe — the whole-car/wholesale online-auction model Copart competes with outside its insurance-salvage core. Having sold ADESA's US physical auctions to Carvana in 2022, OPENLANE is now digital-first, which makes its filings the cleanest read on the size and digitization of the wholesale (dealer-to-dealer and off-lease) market that Copart's non-insurance business chases.
OPENLANE pegs the US/Canada wholesale used-vehicle TAM at roughly 15 million vehicles, defining the whole-car pool Copart's non-insurance business competes for — distinct from Copart's salvage/total-loss market. The 'leading digital wholesale marketplace' label is a self-assessment, not a measured share.
OPENLANE Form 10-K (FY2025), Item 1 Business — 'Our Industry': We believe the U.S. and Canadian wholesale used vehicle industry has a total addressable market of approximately 15 million vehicles, which can fluctuate depending on seasonality and a variety of other macro-economic and industry factors. […] There is a large used vehicle marketplace industry in North America that includes physical, digital and hybrid marketplaces, independent wholesalers, and ancillary wholesale channels operated by large retail automotive groups, rental companies and financial institutions. OPENLANE is a leading digital wholesale marketplace and offers a compelling value proposition in terms of speed, ease and outcomes for buyers and sellers.
p. 5 · Read in context →
Quantifies OPENLANE's throughput — roughly 1.5 million vehicles and $28.8 billion GMV in 2025 across the US, Canada and Europe — a concrete benchmark for sizing Copart's whole-car and international remarketing volumes. GMV is gross transaction value, not revenue, so it is not directly comparable to Copart's reported revenue.
OPENLANE Form 10-K (FY2025), Item 1 Business — 'Overview': OPENLANE is a leading digital marketplace for wholesale used vehicles operating in the United States, Canada and Europe. Our technology and people connect the leading automotive manufacturers, dealers, rental companies, fleet operators, captive finance and lending institutions as buyers and sellers to facilitate approximately 1.5 million annual vehicle transactions with a gross merchandise value ("GMV") of $28.8 billion in 2025. GMV represents the total dollar value of vehicles sold through our marketplaces.
p. 4 · Read in context →
OPENLANE's CEO states that over 70% of US wholesale dealer-to-dealer volume still transacts physically, framing digital penetration as early — the same physical-to-digital runway Copart's online model targets. The 'leader' and share claims are management assertions, not audited data.
Peter Kelly, CEO, Q&A (Q3 2025 earnings call): While we still hold a relatively small market share in U.S. D2D, it represents the largest total addressable market available to us, making it a significant growth opportunity. […] As for the drivers behind this growth, we believe the industry is transitioning from a primarily physical model to a more digital model. Currently, over 70% of volumes are still physical, but the digital share is increasing, and we are a leader in this space.
p. 5 · Read in context →
ACV Auctions, Inc. (ACVA)
ACV Auctions runs a digital dealer-to-dealer wholesale vehicle auction marketplace built around online live auctions, condition inspections, transport and financing — a direct competitor to Copart's whole-car/wholesale online-auction business and a fellow proponent of the physical-to-digital migration thesis. It is a growth-stage share-taker, so its filings articulate the digitization opportunity in the wholesale channel adjacent to Copart's salvage core.
ACV's filing calls digital penetration of the wholesale market early-stage and lagging retail, and claims it will capture a disproportionate share of the shift — the clearest written statement of ACV's penetration thesis in the same whole-car arena Copart plays in. Aspirational, but from a filed 10-K.
ACV Auctions Form 10-K (FY2025), MD&A — Key Factors Affecting Performance: Wholesale vehicle online penetration is in the early stages, lagging the consumer automotive market, and we expect more dealers and commercial partners to source and manage their inventory online. As the digitization of the wholesale automotive market accelerates, we believe that our digital marketplace is well positioned to capture a disproportionate share of that growth.
p. 46 · Read in context →
ACV's CEO puts roughly 70% of dealer wholesale still clearing through physical auctions, with the stated goal of converting that volume to digital — the size-of-the-prize framing behind ACV's and Copart's online-auction positioning. Management assertion, not audited fact.
George Chamoun, CEO, Q&A (Q4 2025 earnings call): It's important to note that dealer wholesale is still largely driven by physical auctions, which account for 70% of the business. Our goal remains to shift more of this physical auction business to digital platforms, and we are seeing progress in that area due to our differentiated offerings.
p. 4 · Read in context →
ACV reports 213,000 units sold in the quarter and claims accelerating share gains, plus expansion into commercial wholesale (via Project VIPER) — a move toward the fleet/off-lease consignor supply that whole-car auction players contest. The unit count is reported; 'market share gains' and 'accelerated' are management characterizations.
George Chamoun, CEO, prepared remarks (Q1 2026 earnings call): Third, we're gaining traction with our emerging growth initiatives, including the initial launch of VIPER and expanding our TAM into commercial wholesale. […] Even with weather impacts, our market share gains accelerated throughout the quarter, selling 213,000 vehicles, exceeding a difficult comparison in Q1 2025.
p. 1 · Read in context →
LKQ Corporation (LKQ)
LKQ is the largest provider of recycled and alternative collision parts and one of the biggest buyers of salvage vehicles at auction. It sits on the opposite side of the total-loss/repairable decision from Copart: its 10-K discloses that it sources most recycled inventory by bidding at third-party salvage auctions, and its management explains in detail the estimate-to-used-car-value threshold that routes a damaged car into a salvage auction (good for Copart) versus a repair (good for LKQ). An adjacent ecosystem participant and major auction buyer, not a head-to-head auction operator — but its commentary directly illuminates the driver of Copart's salvage supply.
LKQ's CEO spells out the economic threshold that determines whether a damaged vehicle is repaired or 'totaled out' — the same total-loss decision that generates Copart's salvage-auction supply. The mechanism cuts the opposite way for the two companies: rising used-car values push more cars below the total-loss threshold into repairs (LKQ parts demand) and out of the salvage pool (a Copart headwind). Management commentary on market mechanics, from a party on the repairable side.
Justin Jude, President & CEO, Q&A (Q1 2026 earnings call): The biggest benefit and the most real-time response that we get on improving repairable claims is on the used car side. So through Q1, used car prices went up 3.6%, 6.2% alone in March. If you think about the estimating process, as soon as an estimate is written, it's immediately compared to that used car value. If it's below the threshold, it turns into a repairable claim. If it's above the threshold, it gets totaled out. So when we see used car prices like in March grow 6.2%, that immediately reflects into the repairable claims.
p. 5 · Read in context →
A buyer's-eye corroboration of Copart's market power: LKQ discloses it sources most recycled inventory at third-party salvage auctions, without contracts, and flags that 'a small number of companies control a large percentage of the salvage auction market' — the concentrated platforms (Copart and IAA) it depends on and could see raise fees. A fact-based risk disclosure that positions LKQ as a customer of, not a rival to, Copart's auctions.
LKQ Form 10-K (FY2025), Item 1A Risk Factors: Most of our wholesale recycled inventory is obtained from vehicles offered at salvage auctions that are owned and operated by third party companies. We do not typically have contracts with these auction companies. According to industry analysts, a small number of companies control a large percentage of the salvage auction market. If an auction company prohibited us from participating in its auctions, began competing with us, or significantly raised its fees, our business could be adversely affected through higher costs or the resulting potential inability to service our customers. […] In addition, there is a limited supply of salvage vehicles in North America, and thus the costs to us of these vehicles could increase over time.
p. 15 · Read in context →
CarMax, Inc. (KMX)
Beyond its used-car retail stores, CarMax operates one of the largest wholesale vehicle auctions in the US — 538,203 vehicles sold in fiscal 2026, conducted primarily virtually since fiscal 2021. The overlap with Copart is the wholesale-auction operation, but the model is structurally different: CarMax auctions are captive, disposing of aged trade-ins that fail its retail standards rather than insurance total-loss vehicles. The retail store experience is out of scope except as the source of auction supply.
CarMax's own Competition section places its auctions against 'other automotive in-person and online auctions' — the category Copart occupies — and confirms it has run those auctions primarily virtually since fiscal 2021, mirroring the online-bidding model. It also flags the key contrast: CarMax auctions are fed by captive appraisal buys that fail retail standards and skew older/higher-mileage, versus Copart's insurance-driven salvage flow.
CarMax Form 10-K (FY2025), Item 1 Business — 'Competition': Our high volume of appraisal purchases, further supported by our online instant appraisal offers and MaxOffer, supplies not only a large portion of our retail inventory, but also provides the scale that enables us to conduct our own wholesale auctions to dispose of vehicles that do not meet our retail standards. […] Our wholesale auctions compete with other automotive in-person and online auctions. These competitors auction vehicles of all ages, while CarMax’s auctions predominantly sell older, higher mileage vehicles. Since fiscal 2021, our wholesale auctions have primarily been conducted virtually.
p. 8 · Read in context →
Highlights the structural difference from a consignment platform like Copart: CarMax owns 100% of the vehicles it auctions, yielding a ~99% sell-through rate. Copart, by contrast, is predominantly a fee-based agent auctioning vehicles it does not own for insurance sellers — a distinction that matters when comparing sell-through, inventory risk and margin structure.
CarMax Form 10-K (FY2025), Item 1 Business — vehicle sourcing: Those vehicles that do not meet our retail standards are sold to licensed dealers through our wholesale auctions. Unlike many other auto auctions, we own all the vehicles that we sell in our auctions, which allows us to maintain a high auction sales rate. This high sales rate, combined with dealer-friendly practices, makes our auctions an attractive source of vehicles for licensed dealers. […] For fiscal 2026, our average auction sales rate was approximately 99%.
p. 7 · Read in context →
Carvana Co. (CVNA)
Carvana is primarily an online used-car retailer, but its 2022 acquisition of ADESA's US physical auction network (56 locations) and its build-out of ADESA Clear, a digital wholesale auction, make it an indirect competitor in the whole-car wholesale auction and remarketing market. The overlap is whole-car dealer wholesale, distinct from Copart's insurance-salvage core; the retail e-commerce business is out of scope.
Carvana is building ADESA Clear, a digital wholesale auction on top of the 15 ADESA sites where it has added reconditioning — the infrastructure layer most directly analogous to Copart's online-bidding platform, though aimed at whole-car dealer wholesale rather than salvage. Evidence Carvana is investing in the online-auction and remarketing capabilities where Copart competes. 'Best-in-class' is management's own characterization, without third-party benchmarking.
Ernest Garcia, CEO, prepared remarks (Q3 2025 earnings call): Over the last 18 months, we've added reconditioning capacity to 15 ADESA locations, allowing us to position inventory closer to our customers, reducing customer delivery time by a day in the last 5 quarters. We've developed our digital auction capability, ADESA Clear, delivering a best-in-class digital auction experience to our wholesale customers
p. 1 · Read in context →
The 10-K states the ADESA acquisition scale — 56 physical auction locations being rebuilt for combined retail and wholesale use — and frames Carvana's ~1.6% share of a ~37 million-transaction used-vehicle retail market. Note the TAM cited is the retail market, not the wholesale/salvage auction pool where Copart operates, so the 'long runway' framing should be read with that caveat.
Carvana Form 10-K (FY2025), Item 1 Business: Further, the acquisition of ADESA US Auction, LLC in 2022 provided us with 56 additional locations, which we have been building out to increase our reconditioning capacity and the number of inventory pools closer to customers. We are integrating ADESA sites to combine retail and wholesale capabilities within single locations over time, enhancing both retail production and wholesale disposition. […] With more than 37 million transactions in 2024, according to Cox Automotive, the used vehicle retail market represents a massive, highly fragmented industry, of which Carvana currently has an estimated market share of only approximately 1.6%.
p. 7 · Read in context →
More peer documents
Q2_FY2025 — 7 pages · CEO describes IAA's catastrophe-surge playbook — overflow capacity via NASCAR sites and Ritchie Bros. yards — a direct parallel to Copart's CAT-response capability that management calls a 'sustainable competitive advantage'. · Open →
Q3_FY2024 — 8 pages · CEO Peter Kelly claims a commercial seller converting ~95% of inventory on OPENLANE and a 'substantial premium' versus physical auction — the digital-beats-physical value narrative shaping the wholesale channel. · Open →
Q3_FY2025 — 11 pages · CEO frames the competitive set as 'hundreds of physical auctions and a few digital ones' with buy fees rising industry-wide — a read on wholesale-auction fee dynamics and the small digital-competitor cohort. · Open →
Q3_FY2026 — 16 pages · CFO quantifies wholesale volume, ASP and per-unit gross profit compression driven by 'steep depreciation' — shows how sensitive CarMax's whole-car auction economics are to used-vehicle price swings versus Copart's fee model. · Open →
Q2_FY2025 — 11 pages · CEO discusses new state 'right-to-appraisal' laws (Texas, New Jersey) that tend to raise contested total-loss valuations and shift more vehicles into repairable claims — a regulatory watch-item for salvage-vehicle supply into Copart's auctions. · Open →
Source: S&P Capital IQ consensus via Xpressfeed · Generated 2026-08-03.
Consensus Tape
Consensus trimmed Copart's forward numbers over the past six months — FY2027 revenue is down about 5% and FY2028 down 6% from where they sat in February — but the cuts have essentially stopped over the most recent quarter. The company keeps clearing EPS: five straight quarterly beats into FY2026, even as revenue ran light of consensus in four of the last seven quarters. Outer-year coverage, FY2028 and FY2029, rests on a handful of analysts.
FY2027 Revenue (consensus)
FY2027 EPS, normalized
Street Target (mean)
Source: derived from vendor data.
Consensus cut forward estimates ~5% over six months, then stopped
The forward tape moved one way this year: down. FY2027 revenue consensus fell 4.9% from its February level, and FY2028 revenue fell 6.4%; on the earnings line, FY2027 EPS came down 6.6% and FY2028 EPS 3.3%. Almost all of that happened in the first half of the window — over the most recent quarter FY2027 revenue and EPS are within 0.2% of today, and FY2028 has not moved at all in the past month. The shape is a downgrade cycle that has flattened, not one still deteriorating.
Source: derived from vendor data.
That both revenue and EPS were cut together points to a demand-side markdown rather than a margin reset; the tape carries the direction and magnitude, not the cause.
Copart keeps beating on EPS while revenue runs light
The beat/miss record splits by line. Normalized EPS has topped consensus in six of the last seven quarters — five in a row from FY2025 Q1 through FY2026 Q1, with a standout 13.3% beat in FY2025 Q4 — interrupted only by a single-quarter miss in FY2026 Q2. Revenue tells a softer story: it missed consensus in four of the last seven quarters, including a run of four straight small misses. Beating earnings while revenue lands short is a margin-quality signal, and it sits alongside the revenue-led downgrades above.
Source: derived from vendor data.
A flat FY2026, then reacceleration through FY2029
The consensus trajectory is not a straight line. Revenue and EBITDA are seen essentially flat in FY2026 — revenue consensus of $4,645M is within half a percent of FY2025 — before growth resumes: revenue +3.9% in FY2027, +8.4% in FY2028 and +7.2% in FY2029, a roughly 4.7% four-year CAGR. EPS is expected to compound a little faster, from $1.55 in FY2025 to $1.97 in FY2029, about a 6% CAGR, helped by the below-the-line leverage the beat pattern already hints at.
Source: derived from vendor data.
Coverage thins to a handful of analysts by FY2028
Confidence in the outer years should be read against how few analysts stand behind them. Revenue and EPS carry 11 to 13 estimates through FY2027, then drop to four contributors in FY2028 and two in FY2029; EBITDA is thinner still, at three estimates in FY2028 and a single one in FY2029. Even where coverage is deep, FY2027 EPS spans $1.55 to $1.78 across 13 analysts — a genuinely wide disagreement on the near-forward earnings line, not just outer-year noise.
Source: derived from vendor data.
The street: mildly positive, with targets spanning 2x
Positioning is constructive but not crowded. Of 13 ratings, seven are positive (five buy, two outperform), five are hold and one is negative. Price targets, from 10 estimates, average $40.30 with a $41 median, but the range is wide — a low of $26 against a high of $55, a 2.1x spread that signals real disagreement on value. This feed carries no current share price, so no upside or downside to it is implied here.
Source: derived from vendor data.
For driver-level broker models and segment detail, see the Visible Alpha tab.
Visible Alpha broker models via S&P Xpressfeed · 4 brokers · 319 line items · freshest revision 2026-06-09.
Broker Models
Broker models see Copart's revenue stalling in FY-2026 — essentially flat — before reaccelerating about 5% in FY-2027 and 7% in FY-2028. The lift is international: overseas service revenue compounds near 10% a year while the US line barely grows. FY-2026's pause was volume, not price — roughly 6% fewer cars, offset by higher revenue per car. Service auctions still throw off almost all the profit. Read all of this as a thin panel: at most four brokers, and the unit detail rests on one.
FY-2027 Revenue
FY-2027 Revenue Growth
FY-2027 Operating Margin
FY-2027 EBITDA
Source: derived from vendor data.
After a flat FY-2026, the modeled top line reaccelerates
The consensus path is not a straight line. Revenue is modeled essentially flat in FY-2026 (-0.2% on the mean), then reaccelerates to +4.8% in FY-2027 and +6.8% in FY-2028. The dispersion around the level is narrow — brokers agree on where revenue lands even where they disagree on what drives it — so the debate is about composition, not the headline.
Source: derived from vendor data.
International, not the US, is the modeled growth engine
Underneath the flat headline, the two geographies pull in opposite directions. International service revenue is modeled to compound about 10% a year — +9.8%, +11.1%, then +8.1% — while US service revenue actually dips in FY-2026 (-2.1%) and grows only low-single-digits thereafter (+3.3%, +6.0%). International is roughly a seventh of service revenue today, but it is where essentially all of the modeled service growth comes from.
Source: derived from vendor data.
The FY-2026 stall was fewer cars, not weaker pricing
The single broker who models units splits the flat service line cleanly: volume falls about 6% in FY-2026 (roughly 4.4 million cars versus 4.7 million), while revenue per car rises 7.5% to about $902. In FY-2027 that reverses only slightly — volume edges up 1.0% and revenue per car climbs another 4.0% to about $939. The read is that Copart is holding revenue through price and mix as auction volumes soften.
Source: derived from vendor data.
Service auctions are the profit; vehicle sales add scale, not margin
Copart books two very different lines. Service auctions are the whole profit story — the models put service gross profit near $2.0B a year. Vehicle sales, though several hundred million in revenue, contribute a sliver of gross profit: about $77M in FY-2026, rising toward $91M by FY-2028. In other words, the low-margin principal-purchase line adds top-line scale but almost nothing to the bottom line, which is why the service growth story above is what matters for value.
Source: derived from vendor data.
Earnings grind higher; free cash flow is the real disagreement
Profitability is the settled part of the model. EBITDA rises +6.7% then +7.3%, operating income advances at a similar clip, and operating margin holds in a tight 36% to 37% band throughout — so the margin structure is not where the debate lives.
Source: derived from vendor data.
Free cash flow is where the two brokers who model it part ways. After rising about 12% in FY-2026, free cash flow is modeled to fall roughly 8% in FY-2027 even as earnings keep climbing — a rare down year for cash, and the range is wide: the low and high models sit far apart, from a floor near the FY-2026 level to a new high. On a per-share basis that is $1.20 in FY-2025, $1.31 in FY-2026 and back to $1.27 in FY-2027.
Source: derived from vendor data.
Headline P&L consensus, momentum and beat/miss live in the CapIQ tab.
Source: S&P Capital IQ transcripts via Xpressfeed · latest indexed call 2026-05-21 · generated 2026-08-03.
Latest call digest
Copart, Inc., Q3 2026 Earnings Call, May 21, 2026 · 2026-05-21T21:30:00
Q3 FY2026 — May 21, 2026. The prepared remarks and the Q&A pulled in slightly different directions. Management led with a familiar contrast: insurance unit volumes kept sliding (global insurance units down 2.7%, U.S. down 4.2%) on what they again framed as a cyclical consumer pullback in auto insurance coverage, yet returns set records — U.S. insurance ASPs rose 4.1% to a seasonally adjusted all-time high, total loss frequency reached 23.6% for the first calendar quarter of 2026, and consolidated revenue grew 2.1% to $1.24 billion with EPS up 2.4% to $0.43. International was the growth story (units up 5.9%, revenue up 14.1%). Capital return was concrete for a change: 43.4 million shares repurchased for over $1.6 billion fiscal year-to-date. Leah Stearns also flagged the launch of domestic long-haul delivery.
In Q&A, analysts largely set the quarter's numbers aside and pressed on durability. Bob Labick opened on fuel/transportation cost exposure and then on whether the post-2020 decline in new-car sales threatens future salvage supply — Jeff Liaw pushed back, arguing supply is a 'layer cake' of many model years and that miles driven, not new-car cohorts, is the variable that matters. Craig Kennison probed the insurance Advisory Board's read on 2026-2027 claims and on AI. The heaviest recurring investor focus was the noninsurance/whole-car business: Jash Patwa and John Healy pressed on its size, the crossover-buyer journey, pure-sale mix mechanics, and — pointedly — whether the Copart/BluCar brand is strong enough to win dealer volume. Management reaffirmed the cyclical framing of the insurance softness, leaned on the noninsurance flywheel, and, as usual, offered no financial guidance.
Participant coverage from the latest call.
| Group | Participants | Count |
|---|---|---|
| Management | Operator; Jeffrey Liaw — Former CEO & Director, Copart, Inc.; Leah Stearns — Senior VP & CFO, Copart, Inc. | 3 |
| Analysts | Bob Labick — President, CJS Securities, Inc.; Craig Kennison — Director of Research Operations and Senior Research Analyst, Robert W. Baird & Co. Incorporated, Research Division; Jash Patwa — Analyst, JPMorgan Chase & Co, Research Division; John Healy — MD & Equity Research Analyst, Northcoast Research Partners, LLC; Jeffrey Lick — MD & Research Analyst, Stephens Inc., Research Division | 5 |
Curated latest-call exchanges; one row per analyst topic.
| Analyst | Firm | Topic | What changed in Q&A |
|---|---|---|---|
| Bob Labick | CJS Securities | Fuel and transportation cost exposure | Asked how rising fuel costs flow through Copart's hybrid tow model and whether surcharges are passed to customers; management described market-by-market rate adjustments across owned, Truck In a Box and third-party capacity. |
| Bob Labick | CJS Securities | Post-2020 SAAR decline and future salvage supply; 5-year growth drivers | Pressed on whether weak new-car cohorts dent salvage volumes in 2027+; management downplayed the link, citing the multi-year installed base and miles driven as the real driver. |
| Craig Kennison | Baird | Insurance Advisory Board read on claims and AI catalysts | Asked what insurance partners expect for 2026-2027 claims and to elaborate on industry catalysts; answer centered on cyclical claims softness and AI on the claims side. |
| Craig Kennison | Baird | International service revenue drivers, including Germany | Probed whether the ~18% international service-revenue growth reflects market strength or Copart-driven remarketing traction; CFO cited U.K., Germany and Canada strength. |
| Jash Patwa | JPMorgan | Whole-car business size and crossover-buyer profile | Asked for the size of the noninsurance/whole-car business and how crossover buyers ramp; management described the discovery journey but again did not quantify the segment. |
| Jash Patwa | JPMorgan | Pure-sale mix — contractual vs. dynamic, and earnings impact | Pressed on whether rising pure-sale mix is contractual and whether it helps earnings; management said it is discretionary, not contractual, and trending to all-time highs. |
| John Healy | Northcoast Research | Whole-car definition and whether the Copart/BluCar brand suffices for dealer ambitions | One of the harder exchanges — questioned the seller sourcing of whole-car units and whether a non-Copart brand is needed to win dealers; management defended the organic, spectrum-climbing approach. |
| Jeffrey Lick | Stephens | Long-haul delivery economics | Asked what the newly emphasized long-haul delivery product entails; CFO cited rapid buyer adoption, ~$15 million of year-over-year facility-ops cost and a favorable margin. |
Theme tracker
Themes are curator-classified across supplied calls.
| Theme | Status | Quarters mentioned | Read-through |
|---|---|---|---|
| Rising total loss frequency as the core growth engine | persisted | Q4 2024, Q1 2025, Q2 2025, Q3 2025, Q4 2025, Q1 2026, Q2 2026, Q3 2026 | Cited on essentially every call as the structural offset to declining accident frequency. The reported industry figure climbed from the high-teens in 2023 toward 23.6% for the first calendar quarter of 2026, and management repeatedly casts Copart's auction returns as an active driver of the trend, not a passive beneficiary. |
| Consumer pullback on insurance coverage / underinsurance | persisted | Q4 2024, Q3 2025, Q1 2026, Q2 2026, Q3 2026 | Emerged as a minor Q&A topic in FY2025 and has since become the central explanation for falling insurance unit volumes. Management consistently frames it as cyclical rather than secular — a claim the volume trend has not yet vindicated. |
| Noninsurance / whole-car growth (BluCar, dealer, fleet and finance) | persisted | Q4 2024, Q1 2025, Q2 2025, Q3 2025, Q4 2025, Q1 2026, Q2 2026, Q3 2026 | A durable growth pillar and, increasingly, the topic analysts press hardest as insurance volumes soften. Management ties it to the same total-loss flywheel — higher-value repairable cars drawing the buyers that also serve rental, fleet and finance sellers. |
| Artificial intelligence | emerged | Q4 2025, Q2 2026, Q3 2026 | Began as an occasional Q&A curiosity about image recognition as far back as FY2024, then moved into CEO prepared remarks as a priority in FY2026 — a ~1,000-engineer bench, named tooling, and AI-enabled total-loss decision tools pitched to insurance carriers. |
| Active share repurchases | emerged | Q2 2026, Q3 2026 | For years management deferred buyback questions while cash accumulated. Repurchases actually began in the second quarter of fiscal 2026 and reached over $1.6 billion (43.4 million shares) fiscal year-to-date by the third quarter — a genuine shift from deferral to execution. |
| Catastrophe-event volume as an active narrative | dropped | Q1 2025, Q2 2025, Q3 2025, Q4 2025 | Hurricane response and CAT-storage capacity were recurring prepared-remark features through fiscal 2025 (notably Helene and Milton). In the fiscal 2026 calls CAT appears only as a prior-year comparison that depresses reported volume growth, not as an active operating story — partly the natural lapping of those storms. |
Guidance ledger
Quotes, calls, and speakers are source-verified; outcomes are curator-classified.
| Verbatim guidance | Call | Speaker | Curator outcome | Outcome note |
|---|---|---|---|---|
| “we'll reach 25% and we'll reach 30%” | Copart, Inc., Q1 2026 Earnings Call, Nov 20, 2025 · 2025-11-20T22:30:00 | Jeffrey Liaw | pending | A long-horizon conviction about industry total loss frequency, not dated financial guidance. Copart declines to give numeric financial guidance. By the first calendar quarter of 2026, reported total loss frequency was 23.6% — still climbing toward, but below, the 25% mark. |
| “we are approaching a run rate of 1 million titles obtained per year” | Copart, Inc., Q4 2024 Earnings Call, Sep 04, 2024 · 2024-09-04T21:30:00 | Jeffrey Liaw | kept | An operational milestone for the Title Express platform. By the Q2 2025 call management stated Copart was processing "well over 1 million titles per year," and later calls describe continued double-digit growth in titles procured on behalf of carriers. |
Q&A pressure map
Question counts and firms are curator tallies; analyst coverage shown above.
| Topic | Questions | Firms | Pressure / response |
|---|---|---|---|
| Insurance volume declines, claims frequency and market-share erosion | 13 | CJS Securities, Baird, Jefferies, JPMorgan, Northcoast Research, Stephens | The dominant line of questioning across the three fiscal 2026 calls — why units keep falling, whether accident-frequency and coverage trends are cyclical or secular, and when volume inflects. Management answers consistently but declines to quantify share, repeatedly noting it does not comment on individual accounts. |
| Noninsurance / whole-car sizing and crossover-buyer economics | 8 | Baird, Jefferies, JPMorgan, Northcoast Research | Analysts pressed repeatedly for the dollar or unit size of the whole-car business and how crossover buyers convert. Management describes the dynamics qualitatively but has not disclosed the segment's size, a gap analysts keep returning to. |
| Capital allocation and buybacks | 3 | Northcoast Research, Stephens | Questions on why now, and whether open-market purchases are the right tool. Management kept the framing generic — buybacks as the long-standing return mechanism, timing driven by valuation and rates. |
Language shifts
Only language evidence verified against the referenced component is shown.
| Observation | Verbatim evidence | Call ID | Component |
|---|---|---|---|
| AI shifted from an occasional Q&A topic to a CEO prepared-remarks priority, with unusually specific tooling references and a headcount claim — a marked escalation in how central management presents its technology posture. | “including my own significant personal engagement in Claude Code and other such platforms” | 1984099380 | 1 |
| Just one quarter before repurchases began, management still used deferral language on buybacks, treating a return of capital as inevitable but undated — a useful marker against which the fiscal 2026 shift to active repurchasing stands out. | “There, for sure, will come a day we do that again.” | 1970006758 | 42 |
| Management's framing of soft insurance volumes has hardened into explicit caution vocabulary tying declining coverage to a growing vehicle fleet as evidence of consumer retrenchment. | “clear evidence of the consumer pullback on insurance coverage” | 2000324320 | 1 |
| Geopolitical risk vocabulary broadened by Q3 2026 from the tariff language of the 2025 calls to explicit references to global conflict, cited as a disruption the diversified international buyer base has so far absorbed (record ASPs held despite it). | “despite the logistical and economic disruptions of global conflict” | 2000324320 | 1 |
The call history reads as a company whose insurance unit volumes have contracted for several straight quarters on a consumer insurance pullback that management insists is cyclical, cushioned by record ASPs, still-rising total loss frequency, and a growing noninsurance/whole-car business. The newer wrinkles — an AI push and, after years of deferral, an active buyback — suggest a management team leaning on returns and capital return while the volume question stays unresolved. Whether the softness is cyclical, as management frames it, or more durable is the central debate the transcripts leave open.
Copart: a compounder, halved
Copart runs the larger of two online auction platforms that insurers and other sellers use to dispose of totaled and salvage vehicles. It is debt-free, holds about $4.8 billion in cash and investments, earns 36% operating margins, and is still controlled by its founders. Yet the stock has fallen roughly 54% from its May 2025 peak — from about $64 to $29 — and now trades near 18 times earnings, well below the multiple it commanded for most of the past decade.
What Copart does
Copart connects sellers of damaged, salvage, and used vehicles with buyers through an internet-based auction platform, operating across the United States, United Kingdom, Germany, Brazil, Canada and several other countries [1]. It was incorporated in 1982, went public in 1994, and today connects roughly one million registered members across more than 185 countries to vehicles consigned at its physical yards [2] [3].
The economic engine is a marketplace, not a car dealership. Most revenue is service revenue — auction and auction-related fees charged to sellers and buyers on each transaction, recognized net rather than on the gross value of the car [4]. Service revenue was 85% of the FY2025 total; vehicles Copart buys and resells for its own account (mostly in the U.K.) make up the remaining 15% [5].
Who supplies the cars matters for durability. In FY2025, 81% of the vehicles Copart processed came from insurance companies [6]. When a car is damaged, the insurer's adjuster compares the cost of repair against the vehicle's pre-accident value less its salvage value; if repair costs more, the car is declared a total loss and assigned to a remarketer like Copart [7]. Because modern vehicles carry ever more expensive electronics, cameras, sensors and safety structures, a growing share of accidents cross that total-loss threshold — a slow, structural driver of the volumes Copart handles [8].
The competitive field is narrow. In North American salvage, Copart's principal rival is RB Global's Insurance Auto Auctions subsidiary; broader vehicle remarketing also includes Carvana, Manheim, OPENLANE and ACV Auctions, and dismantlers such as LKQ that can buy salvage directly and bypass the auction entirely [9]. In practice, salvage auctions in the U.S. are close to a two-firm market, built on hundreds of licensed vehicle yards, insurer relationships, and a national buyer base that are slow and costly to replicate.
The economics
Copart has compounded revenue at roughly 15% a year over the past four fiscal years, from $2.7 billion in FY2021 to $4.6 billion in FY2025, with operating income rising in step to $1.7 billion [10].
Source: total revenue derived from segment disclosures; operating income and the $4.6B / $1.7B FY2025 figures per the FY2025 Form 10-K [11].
The margins are the tell of a genuine marketplace: 36% operating and 33% net in FY2025 [12]. But the direction has softened. Operating margin has slipped every year since a pandemic-era peak of 42% in FY2021, as facility operating costs rose from 39% to 42% of revenue [13].
Source: derived from reported segment revenue and operating income, FY2021–FY2025 10-Ks; the 36% / 37% / 39% progression is stated directly in the FY2025 MD&A [14].
Cash generation is strong and improving in absolute terms: operating cash flow reached $1.8 billion in FY2025, up 22% [15]. Free cash flow of $1.2 billion converts about 79% of net income, held back by an unusually heavy capital program — Copart owns rather than leases most of its land, so it spends heavily on acquiring and developing vehicle yards.
A balance sheet built to survive
For an investor who wants the chance of failure near zero, the balance sheet is the headline. At July 31, 2025 Copart held $2.78 billion in cash and $2.01 billion in held-to-maturity securities — roughly $4.8 billion of liquid assets — against total liabilities of just $883 million, none of it financial debt [16]. Stockholders' equity is about $9.2 billion on $10.1 billion of assets, and the current ratio is above eight [17].
Cash & Investments ($M)
Total Liabilities ($M)
Shareholders' Equity ($M)
Net Income FY2025 ($M)
Free Cash Flow FY2025 ($M)
Source: FY2025 Form 10-K, Consolidated Balance Sheets [18]; operating and free cash flow per MD&A [19].
A company that carries no debt and sits on $4.8 billion of cash and Treasuries does not go bankrupt in any ordinary sense. The liabilities on the sheet are operating in nature — payables, deferred revenue, taxes, and small lease obligations [20]. Whatever risks this business carries, solvency is not among them.
Founders still hold the shares
Copart is not a professionally managed orphan; it remains founder-anchored. Willis J. Johnson founded the company in 1982 and is Chairman; A. Jayson Adair, a founder since 1992, is Executive Chairman, having moved out of the co-CEO seat in a planned 2023 succession that installed Jeffrey Liaw as CEO [21]. The company itself frames a "founder-led culture" as a core competitive advantage [22].
The alignment is financial, not just rhetorical. As of October 2025, Johnson beneficially owned 55.7 million shares (5.75%) and Adair 30.6 million (3.14%) — together roughly $2.5 billion of stock at the current price — a combined stake larger than any single institutional position except Vanguard's index holdings [23]. Adair drew a salary of $1 in FY2025 [24]. Whether that alignment has produced disciplined capital allocation is a question for a later chapter; the ownership itself is real.
The drawdown and the de-rating
Copart is one of the great compounders of the modern market: a split-adjusted 15 cents at its 1994 debut became $64 by May 2025. Since that peak it has fallen about 54%, to $29 as of late July 2026, near its 52-week low.
Source: daily price data as reported; 2026 value is the 31 July 2026 close. Split-adjusted history.
Two things drove the re-rating, and both are visible in the numbers. First, growth has stalled: after years of low-teens expansion, quarterly revenue ran roughly flat year-over-year through fiscal 2026 (the second quarter down about 3.5%, the third up about 2%, per reported quarterly results). The FY2025 filing already flagged one mechanism directly — on the international side, some sellers shifted away from a purchase-contract model toward consignment, reducing reported volume [25]. Alongside that, insurers have been assigning fewer vehicles as elevated auto premiums led some drivers to trim coverage, and recent comparisons run against earlier catastrophe-driven volumes. Second, the margin compression above meant earnings grew more slowly than the headline suggests. Forward estimates now sit essentially flat — consensus EPS of about $1.58 for FY2026 against $1.59 delivered in FY2025.
At $29 on about $1.59 of earnings, Copart trades near 18 times profit and roughly 14 times operating income on an enterprise-value basis, once its $4.8 billion of net cash is stripped out. For most of the last decade the shares changed hands at 30 to 40 times earnings.
Source: multiples derived from reported FY2025 earnings and balance sheet [26] and current market price (price data as reported).
That valuation reset deserves a fair hearing rather than a reflexive dismissal. A rule that avoids "high flyers and very expensive stocks" was built for a company priced at 40 times earnings; it does not obviously bind a debt-free, 36%-margin marketplace at 18 times, with a fifth of its market value in cash. The counter-fact is equally plain, and equally on the page: if insurance assignment volumes have entered a structurally slower era — and if driver-assistance and, eventually, autonomous vehicles reduce accident frequency over time — then a mid-teens multiple on flat earnings is not a bargain but a fair price for a maturing business.
The question this report works through
Copart is a debt-free, founder-controlled duopolist in salvage-vehicle auctions whose shares have fallen roughly 54% from their 2025 peak to about 18 times earnings; the question this report works through is whether that drop is a durable compounder available at an unusual discount, or the market correctly repricing slower insurance volumes and a permanently lower growth rate.
Everything that follows tests one side of that question or the other: how wide and durable the moat around the salvage duopoly really is; whether the recent volume and margin softness is cyclical or structural; what the founders and management have done with the cash the business throws off; and what the current price actually implies for future growth. The pieces that decide it — a fortress balance sheet, a narrowing competitive field, a genuine but slowing set of tailwinds, and a valuation that has already come a long way down — are all in view. What remains is to weigh them.
Financials and Estimates
Copart's last three fiscal years read as a debt-free machine still compounding: revenue rose from $3.87 billion to $4.65 billion and diluted EPS from $1.28 to $1.59, all self-funded. But the pace has downshifted — from a pandemic-era 30% surge to a steady ~10%, and consensus now models a roughly flat fiscal 2026 before low-single-digit growth resumes. Earnings quality improved even as the top line cooled, with free-cash conversion rising and interest on the cash pile now supplying close to a tenth of pre-tax profit.
Three years of results
Fiscal 2025 (year ended July 31, 2025) closed with $4.65 billion of revenue, $1.70 billion of operating income, and $1.55 billion of net income attributable to Copart — a 13.9% earnings gain on 9.7% revenue growth [1].
Revenue ($M)
▲ 9.7% YoY
Net Income ($M)
▲ 13.9% YoY
Diluted EPS
▲ 13.6% YoY
Free Cash Flow ($M)
▲ 28.0% YoY
Source: FY2025 Annual Report (Form 10-K), Consolidated Statements of Income [2] and Consolidated Statements of Cash Flows [3].
The three-year income statement shows a business growing profit faster than sales. Operating income advanced 7.9% in fiscal 2025 while net income rose 13.9% and diluted EPS 13.6% — the wedge between them is a growing stream of interest income and a lower tax rate, discussed below [4].
Source: FY2025 Annual Report (Form 10-K), Consolidated Statements of Income; margins derived from reported figures [5].
Operating margin slipped from 38.4% to 36.5% over the three years — partly $56 million of one-time hurricane (Helene and Milton) catastrophe costs in facility operations during fiscal 2025 — while net margin actually rose to 33.4% [6]. The consolidated statement carries no financial debt; growth was funded entirely from operating cash flow.
The growth downshift
The revenue trajectory is the crux of the report's growth question. Growth ran at 30% in fiscal 2022 as used-vehicle values spiked, then settled into a remarkably consistent ~10% band for three years, and consensus now models a roughly flat fiscal 2026 before a return to low-single-digit growth.
Sources: FY2023–FY2025 reported revenue from FY2025 Annual Report (Form 10-K), Consolidated Statements of Income [7]; FY2021–FY2022 from prior-year 10-K filings, as reported; FY2026E–FY2027E consensus estimates, as reported.
Sources: derived from reported revenue — FY2023–FY2025 per the FY2025 10-K [8], FY2021–FY2022 from prior-year 10-K filings; FY2026E–FY2027E consensus estimates, as reported.
Underneath the flat headline, the mix tells the story. Fiscal 2025's 11.4% service-revenue growth came from both higher revenue per car and volume, while vehicle sales — Copart buying and reselling cars on principal rather than on consignment — were flat as international sellers shifted to the consignment model [9] [10]. Fee-based service revenue is now 85% of the total, up from 83% in fiscal 2023 — the asset-light core keeps taking share of the revenue base [11].
The stall became visible in fiscal 2026's first three quarters, which have been roughly flat against a year earlier. The pressure is on unit volume, not price: management reported global insurance unit sales down 2.7% in the third quarter (down 1.9% excluding prior-year catastrophe volume), and U.S. insurance volume down 4.2%, following a weaker second quarter in which global insurance units fell 9% [12] [13].
Source: quarterly revenue by geography and type, per company filings, as reported.
Management's own framing is that the volume dip is cyclical, not structural: it attributes softer insurance assignments to shifts in policies-in-force and exposure, and maintains that "the long-term growth algorithm for our insurance business remains very much intact," because gradual declines in accident frequency are "more than offset by increases in total loss frequency" [14]. Whether that holds is what a durable-compounder read is most sensitive to; the total-loss-frequency tailwind sits in the industry chapter to come.
Quality of earnings
The three years improved on cash conversion. Free cash flow rose to $1.23 billion in fiscal 2025 — 79% of net income, up from 68% two years earlier — as operating cash flow jumped 22% while capital expenditure on owned land and yards held near $0.57 billion [15].
Source: derived from reported financials, FY2023–FY2025 10-Ks (income statement [16], balance sheet [17]).
Two of those lines deserve a caveat. Net interest income climbed from $65.9 million to $178.9 million across the three years and now equals about 9% of pre-tax profit — a genuine cash return, but one that rises and falls with Treasury yields rather than with the auction business [18]. And headline returns have drifted lower — return on equity from 20.7% to about 16.9%, return on capital employed from 23.8% to 18.0% — not because the business earns less, but because a swelling low-yield cash and Treasury balance dilutes the denominators. The operating business still earns a ~36% margin; what a reader is watching decline is a balance-sheet artifact, and how that cash gets deployed is a question for the capital-allocation chapter.
What consensus expects
Copart issues no formal financial guidance, so the forward view rests on sell-side consensus, which extends about two years. It models fiscal 2026 revenue essentially flat at $4.64 billion with EPS of roughly $1.58 — level with fiscal 2025 — then a return to modest growth in fiscal 2027, revenue up 3.9% to $4.83 billion and EPS up 6.2% to about $1.68.
Source: FY2025 actual per Consolidated Statements of Income [19]; FY2026E–FY2027E consensus estimates (13 analysts), as reported.
Price targets frame how divided that view is. Against a $29.12 share price, the consensus 12-month target is a mean of $40.3 (median $41), with a $55 high and a $26 low — a spread wide enough that the analyst community is not agreed on whether the de-rating is finished.
Current Price
Mean Target
High Target
Low Target
Source: consensus analyst price targets, as reported.
The rating split is similarly balanced: of 13 covering analysts, 7 rate the stock buy or better, 5 hold, and 1 strong sell. On consensus numbers the shares trade at roughly 18 times fiscal 2026 EPS — near the low end of the past decade for a business that grew earnings double digits last year, which is the tension the rest of the report works through. The evidence here points to a still-compounding, cash-generative franchise whose growth engine has stalled on volume; the read that would change is a second or third year of falling insurance units, which would move the flat patch from cyclical to structural.
Ratings: 13 analysts — 2 strong buy, 5 buy, 5 hold, 1 strong sell, per consensus data, as reported.
Capital and Control
For most of the past decade Copart returned almost nothing to its owners: no dividend since its 1994 IPO, and no share buyback at all between fiscal 2019 and fiscal 2025 [1]. Cash and Treasuries built to $4.8 billion while the share count drifted higher. In fiscal 2026 that reversed sharply — Copart repurchased $1.6 billion of stock as the multiple fell, and founder Jay Adair returned as chief executive. The stewardship is unusually low-extraction and owner-aligned; what remains unproven is whether the capital return is a durable turn or a one-off.
A decade of accumulation
Copart's operating machine throws off far more cash than the business can absorb. Operating cash flow rose from $991 million in fiscal 2021 to $1.80 billion in fiscal 2025, and the only material claim on it was capital expenditure — roughly $460 million to $570 million a year, spent mostly on acquiring land and building out yards [2]. Acquisitions have been small and infrequent: National Powersport Auctions (2017), a U.K. parts recycler (2022), and a majority stake in Purple Wave (2024), none individually material to the financials [3].
Everything left over was retained. Copart bought back no stock under its program in fiscal 2020 through 2025, its last repurchase having been in fiscal 2019 [4], and it has never paid a dividend, intending "to retain any earnings for use in our business" [5]. The surplus was parked in U.S. Treasury bills: cash plus held-to-maturity securities reached about $4.79 billion at the end of fiscal 2025, against retained earnings that grew from $2.9 billion to $8.1 billion over four years [6]. In effect, the de facto capital-allocation policy became: reinvest what the business can use, and lend the rest to the Treasury at a few percent.
Source: FY2025 10-K, Consolidated Statements of Cash Flows [7]; nine-month figures from the Q3 FY2026 10-Q [8].
The green bar is the story: flat at zero for five straight years, then a step-change in fiscal 2026.
The buyback turns on
In the second quarter of fiscal 2026 Copart began repurchasing stock in the open market and under a 10b5-1 plan [9]. Through the first nine months it bought back 43,433,164 shares at a weighted-average $37.63, totalling $1,632.5 million — its largest capital return ever, and the first repurchase of any size since fiscal 2019 [10]. The effect on the share count was immediate: shares outstanding fell from 967.5 million at the end of fiscal 2025 to 925.8 million by late May 2026, a 4.3% reduction that reversed years of slow drift upward from option exercises [11]. Cash and Treasuries were drawn down from $4.8 billion to about $4.2 billion to fund it [12].
Shares Repurchased (9M FY26)
Amount ($M)
Avg Price
Share Count Change
Source: Q3 FY2026 10-Q, Note 6 Stock Repurchases and cover page [13].
Source: FY2025 10-K stockholders' equity rollforward [14]; Q3 FY2026 10-Q [15].
The timing carries a defensible logic and an honest blemish. Copart declined to buy back stock through fiscal 2020–2025, when it traded at 30–40 times earnings, and stepped in only after the price had roughly halved — the finance chief called it "an opportune time to proceed" and "a sensible way to return capital to shareholders" [16]. Buying near a lower multiple beats buying near a peak. The blemish: the $37.63 average paid still sits above the roughly $29 the shares fetched by the end of July 2026, so the fiscal 2026 repurchases are, for now, underwater — the company bought into a continuing decline. The program is also discretionary rather than a committed framework; management describes repurchases as its "lever to return capital" when valuation is compelling, ranked behind reinvestment and M&A [17], and for the first time now lists "the payment of dividends" among the alternative uses under consideration [18].
One second-order effect is worth noting for anyone modelling earnings: drawing down the Treasury pile trades interest income for a lower share count. Copart already flagged lower interest earned on Treasury bills as a drag on other income in the third quarter [19]. The interest income that has been flattering earnings per share (Financials and Estimates) will fade as the cash is spent, even as fewer shares divide the profit — the two partly offset.
The stewards: owned, not paid
What makes the accumulation easier to read charitably is who is doing it. Copart is run by its founders, and their incentive is the stock, not the salary. Willis Johnson — who founded the company in 1982 and was chief executive until 2010 [20] — and his son-in-law Jay Adair are named as the company's founders [21] and rank among its ten largest holders [22]. As of October 2025, Johnson held 5.75% and Adair 3.14% — together about 86 million shares, worth roughly $2.5 billion at the July 2026 price — and directors and officers as a group held 9.60% [23].
Against those stakes, cash pay is nominal. Adair, as executive chairman, drew a $1.00 annual salary [24]; his roughly $432,000 of total compensation was almost entirely perquisites, chiefly $349,638 for company-mandated aircraft use [25]. Chief executive Jeff Liaw's total pay of about $2.07 million put the CEO-to-median-employee ratio at 46-to-1 [26], modest for a company of Copart's size, and the professional managers' equity is genuinely performance-gated: Liaw's option awards cannot be exercised unless the stock trades at or above $39.28 — a 25% premium to the grant price — for twenty consecutive days, a hurdle unmet at the current price [27]. Stock-based compensation ran just $38.0 million in fiscal 2025, about 2.4% of net income [28], and a clawback policy has applied since 2023. This is a low-dilution, low-extraction ownership culture — the opposite of the equity-heavy pay that erodes per-share value at many peers.
Source: FY2025 Proxy Statement — Summary Compensation Table and Security Ownership [29]. Johnson is compensated as a non-employee director; Liaw's and Stearns' individual holdings are each below 1%.
The control question: the founder comes back
The alignment story gained a twist in mid-2026. On June 29, 2026 Copart announced that Jeff Liaw — its third-ever CEO, appointed only in 2024 — would step down as chief executive and director effective July 31, 2026, and that founder Jay Adair, the executive chairman and a former CEO, would resume the role; Liaw would stay on as a special advisor [30]. Days later the company promoted its U.K. managing director, Jane Pocock, to president. The founder is retaking operational control at the same moment the capital return begins.
For a reader underwriting a founder-run business, this cuts both ways. It deepens the alignment and continuity that anchor a founder-run thesis — the largest individual owners are once again running the company day to day, and Adair's compensation gives him almost nothing to gain except through the share price. It also reverses the orderly, professional-management succession the company had spent a decade building, and concentrates responsibility in founders who are no longer young: Johnson is 78 and Adair 56. The re-engagement is a vote of confidence; the succession question it reopens is real, and there is no institutional answer to it yet.
What the evidence supports, and what would change it
On the axis that protects capital, Copart's stewardship is close to a model: founders with billions at stake and nominal pay, no debt, no dilutive deal-making, disciplined restraint from buying an expensive stock, and equity awards that pay only on appreciation. On the axis that builds per-share value, the record was, until this year, passive — a decade of letting cash compound at Treasury yields well below the mid-teens returns the operating business earns. Fiscal 2026 is the first evidence that management will convert the fortress into per-share value rather than hoard it, and it did so at a sensible entry multiple. That is the more constructive reading, and it is the one the FY2026 actions support.
The main risk to that read is durability. The buyback is discretionary and, so far, modest against a $4.8 billion starting pile; management has drawn down roughly a third of the surplus and could revert to accumulation once the price recovers. The signals that would confirm a genuine turn are concrete: repurchases sustained across fiscal 2027, a formal capital-return framework or the dividend now under open consideration, and a credible long-term succession plan behind the founder's return. A reversion to letting cash pile back up in Treasuries, with the share count creeping higher again, would confirm the passive read — and cap per-share compounding near the organic growth rate of a business whose volumes have stalled.
Salvage Moat
Copart's durability rests on three reinforcing advantages: a global pool of roughly one million buyers that lifts what insurers recover, an owned-yard footprint that is slow and costly to replicate, and deep integration into insurer claims workflows. The clearest proof sits in the margin — 36.5% at the operating line, against near-identical-revenue RB Global's 17.8% [1][2]. The moat looks wide. Its soft spot is that seller ties are relationships, not contracts, and long-run demand depends on total-loss trends.
The Margin Gap
A moat should show up in the numbers, and here it does. Copart and RB Global are the two listed pure-plays in vehicle-auction remarketing, and their most recent fiscal years line up almost exactly on revenue — Copart at $4.65 billion (year ended July 2025), RB Global at $4.28 billion (year ended December 2024). What they do with that revenue is not close.
Copart operating margin
RB Global operating margin
Margin gap
Sources: Copart FY2025 10-K, Consolidated Statements of Income [3]; RB Global FY2024 10-K, Consolidated Income Statements [4].
Sources: Copart FY2025 10-K [5]; RB Global FY2024 10-K [6].
On roughly the same revenue, Copart earned $1.70 billion of operating income to RB Global's $761 million, and $1.55 billion of net income to RB Global's $413 million [7][8]. The comparison is imperfect: RB Global is a blend of Ritchie Bros' commercial-equipment auctions and IAA, the salvage marketplace it bought in March 2023 for about $6.6 billion [9][10]. But IAA is precisely Copart's nearest salvage rival, and even folded inside a larger group it drags the blended margin to less than half of Copart's. RB Global also carries the cost of that deal: $234 million of interest expense in 2024, against Copart's net interest income of $179 million on a debt-free balance sheet [11][12]. A well-capitalized rival has spent the better part of a decade competing head-to-head and still cannot match Copart's unit economics. That gap is the moat, expressed as a number.
The Network Flywheel
The first source of that gap is a two-sided marketplace that gets more valuable as it grows. Copart maintains a database of roughly one million registered buyers — dismantlers, rebuilders, used-car dealers, and exporters — and because its VB3 platform is entirely virtual, a wrecked car in Texas can draw bids from a buyer in Eastern Europe or West Africa without either party moving [13][14]. Copart states the mechanism plainly: the virtual platform "increases the pool of available buyers for each sale, which brings added competition and an increase in the amount that buyers are willing to pay" [15].
That is the flywheel. More buyers raise the winning bid; a higher bid means the insurer recovers more on a totaled car; higher recoveries make Copart the obvious place to send the next assignment; more assignments deepen the inventory that attracts still more buyers. International buyers are the part a domestic-only rival struggles to replicate — foreign importers "now represent a significant part of our total buyer base," and they bid on cars that a local salvage yard could not clear at the same price [16]. The result is the supply concentration behind the whole model: insurers supplied 81% of the vehicles Copart processed in fiscal 2025 [17]. Crucially, Copart earns fees on the transaction rather than buying most cars for its own book, so each incremental sale adds high-margin revenue without inventory risk — the capital-light half of the 36.5% margin.
The Physical Moat
The second advantage is the opposite of capital-light, and that is the point. A virtual auction still needs somewhere to put the cars. Copart operates 281 facilities globally and, unlike its principal rival, owns much of the land under them [18]. Net property and equipment has climbed from $1.9 billion in fiscal 2020 to $3.6 billion in fiscal 2025 as the company steadily bought yards rather than leased them [19].
Source: derived from Copart reported balance sheets, FY2020–FY2025; FY2025 figure per the FY2025 10-K, Consolidated Balance Sheets [20].
Owning the land matters because the land is genuinely scarce. New sites run into "zoning restrictions or difficulties obtaining and maintaining use permits," and Copart warns that when it cannot secure enough capacity it risks damaging "our relationships with insurance companies" — the salvage yard is not a commodity warehouse but the physical link that keeps insurer volume flowing, especially when a hurricane fills every yard in a region overnight [21]. RB Global runs the leaner-looking version: it carried $1.5 billion of operating-lease right-of-use assets at the end of 2024, renting much of the ground Copart owns outright [22]. Ownership ties up capital and holds free-cash-flow conversion below net income — the cost side of this choice, established earlier (Financials and Estimates) — but it also builds a barrier a new entrant would need years and a permitting fight to cross.
Switching Costs, Stated Honestly
The third pillar is the softest, and worth being precise about. Copart is deeply embedded in how insurers process a total loss: it clears salvage titles across every state — "our know-how in the area of title processing is a competitive advantage" — arranges pickup within roughly a day, and hands adjusters an integrated workflow that would be disruptive to rebuild around a competitor [23]. That is a real switching cost, but it is operational, not legal. Copart itself flags "the absence of long-term contractual commitments between us and our sellers," so nothing contractually stops a large insurer from shifting assignments to IAA [24]. The lock-in is that Copart usually returns more money per car and moves it faster — an advantage it has to re-earn on every cycle rather than one it can invoice for. The stable ~36% margin through years of volume wobble is the evidence that, so far, it keeps re-earning it.
What Could Break It
The moat has held against the obvious attack. A well-funded competitor already exists, has owned the number-two salvage platform for years, and still cannot close a nineteen-point margin gap — which separates Copart's structural advantage from mere good execution. The more serious threat is not competitive but demand-side, and it is genuinely two-sided: safer cars and driver-assistance technology should reduce accident frequency over time, which would shrink the pool of damaged vehicles, while the rising cost of repairing those complex cars pushes more of them past the total-loss threshold, which enlarges it. Whether rising total-loss frequency outruns falling accident frequency is central to whether the network keeps compounding or merely holds — and it deserves its own treatment, which Demand Engine takes up.
On the evidence here, Copart clears a wide-moat bar: the advantage is company-specific, quantified in a durable margin gap, and has already survived a serious competitor's attempt to match it. The read that would change is a demand one — if total-loss volumes fell for several consecutive years even as accident rates normalized, the flywheel would slow and the owned-land barrier would protect a shrinking pie rather than a growing one.
The Demand Engine
Behind Copart's fiscal-2026 growth stall sits the structural engine that has driven its volume for decades. U.S. total-loss frequency has climbed from 15.6% of claims in 2015 to 23.1% in 2025, and the same perimeter-mounted safety sensors that gradually reduce accidents raise repair costs enough that rising total-loss frequency more than offsets the accident-frequency decline. [1][2] That climb — about 7.5 percentage points over the decade, and almost 5 points in the last four years to 23.6% in early calendar 2026 [3] — governs how much of a roughly 290-million-vehicle U.S. fleet's accidents become insurer-mediated salvage assignments, the structural pool the whole business feeds on. The tailwind is directional over decades, not guaranteed every year: the FY2025 10-K flags that accident-avoidance systems and, eventually, autonomous vehicles could materially reduce accident rates [4], and a sharp rise in used-car prices suppressed total-loss frequency as recently as 2021–22 before it recovered above its prior highs [5].
Against that durable backdrop, the fiscal-2026 growth stall is a demand-side event: U.S. insurance unit volumes fell between 4% and 10% for three straight quarters — the first sustained decline in years — after the business grew units every year for a decade. The drop separates into two forces pulling in opposite directions: the secular total-loss tailwind above, and a cyclical headwind, consumers shedding insurance coverage as premiums spiked. On the evidence in the corpus, the softness reads as mostly cyclical, with a real but slow-moving structural caveat — a cyclical pause and a permanent downshift in the growth rate are not the same thing.
The secular tailwind: total-loss frequency
Copart's long-run volume depends less on how many accidents happen than on what share of them end in a total loss. When an insurer declares a damaged vehicle a total loss, it flows to a salvage auction; when it repairs the vehicle, it does not. That total-loss frequency has risen for decades, and the recent readings extend the trend.
U.S. total-loss frequency, 2015
U.S. total-loss frequency, 2025
Change over the decade
Source: Q2 FY2026 earnings call, CEO prepared remarks, citing CCC data — 15.6% in calendar 2015 versus 23.1% in calendar 2025 [6].
Sources: Q1 FY2025 call (21.7% for 3Q CY2024) [7]; Q1 FY2026 call (22.6% through Sept 2025) [8]; Q2 FY2026 call (24.2% for 4Q CY2025) [9]; Q3 FY2026 call (23.6% for 1Q CY2026) [10].
The quarter-to-quarter figures are seasonal — total-loss frequency runs higher in winter — but the year-over-year comparisons are consistently positive, and over four years the metric rose almost five full percentage points [11]. Management's own framing is that gradual declines in accident frequency have historically been "more than offset by increases in total loss frequency" [12].
The mechanism is specific, and it is the same technology that reduces accidents. Modern safety systems — lane-departure sensors, cameras, radar — sit on the perimeter of the vehicle, where they are cheapest to damage and most expensive to replace, so each new vehicle vintage is more likely to be totaled after a given collision [13]. Copart argues it is not a passive beneficiary here: by finding higher salvage values through its global buyer network, it makes the total-loss path more economical for insurers to choose, and thereby helps push the frequency up [14]. That claim ties directly to the auction-liquidity moat in Salvage Moat.
The stall, measured
For fiscal 2025 as a whole, U.S. insurance volume still grew 4.2% [15]. The turn came in the back half: the fourth quarter of fiscal 2025 was already down 2.1%, and fiscal 2026 opened with the sharpest declines the company has reported in the corpus.
Source: Q1–Q3 FY2026 earnings calls, CEO prepared remarks — reported and excluding catastrophe volumes [16]; [17]; [18].
The reported line is noisy because the prior-year base included heavy catastrophe volumes from Hurricanes Helene and Milton; stripping those out gives the cleaner read. On that basis the decline is real but sequentially moderating — U.S. units down 7.3% in the first quarter, 4.8% in the second, 3.0% in the third [19]. Management flagged the improvement directly, citing "a moderation in some of these trends among U.S. insurance carriers in recent quarters" [20]. This is the volume evidence behind the flat revenue and the de-rating documented in Financials and Estimates.
The cyclical headwind: consumers dropping coverage
The tailwind is intact, yet volumes fell. Management's explanation is that a rising share of accidents never enters the insurer-mediated total-loss funnel because the driver is no longer carrying collision coverage. Auto premiums rose faster than most other components of consumer spending after 2022, and, on a lag, households responded by downgrading to liability-only policies or dropping insurance altogether [21]. A vehicle that would have become a total-loss assignment is instead repaired out-of-pocket or scrapped through other channels.
The corpus offers a clean signature of this pullback: the count of insured exposure is shrinking even as the vehicle fleet grows.
Source: Q3 FY2026 earnings call, CEO prepared remarks, citing ISS Fast Track — earned car years down 4% against a 1.4% larger vehicle fleet [22].
Earned car years — a measure of insured vehicle-time — fell about 4% year-over-year while vehicles in operation grew 1.4% [23]. Paid collision-claim frequency fell 7.5% over a comparable period [24], and CCC reports that a quarter of repairs are now self-pay — enough that it launched a buy-now-pay-later product for consumers absorbing their own repair bills [25].
The case for calling this cyclical draws on the long record: the share of uninsured and liability-only motorists has trended down for more than 30 years as coverage deepened, with the current uptick a premium-driven wobble inside that secular decline [26]. Management describes the retrenchment as "cyclical and likely counter-inflationary" — as rate increases moderate, coverage tends to rebuild [27]. The sequential moderation in the volume chart above is consistent with that. The honest counter is that this is management's characterization of an ongoing affordability squeeze; the corpus contains no independent forecast of when premiums ease, and a second full year of falling units would start to look structural rather than cyclical.
Pricing power held the line
Volume fell, but revenue did not, because price moved the other way. U.S. insurance average selling prices reached seasonally-adjusted record highs through fiscal 2026 — up 8.4% year-over-year in the first quarter and 4.1% in the third — even as industry-wide used-vehicle values normalized from their 2021–22 peak [28]; [29].
U.S. insurance ASP, Q1 FY2026 YoY
U.S. insurance ASP, Q3 FY2026 YoY
Source: Q1 and Q3 FY2026 earnings calls, CEO prepared remarks — record U.S. insurance average selling prices [30]; [31].
Because Copart's service fees scale with the auction price, rising selling prices lift revenue per unit, which is why nine-month fiscal-2026 revenue held roughly flat against a mid-single-digit unit decline (see Financials and Estimates). That pricing rests on Copart's global export buyer base, and the tariff, currency, and import-ban exposure that comes with leaning on it is taken up in Export Dependence.
The structural caveat, and what would change the read
Two structural risks sit behind the cyclical story, and the company names both in its 10-K. First, a "material reduction in accident rates" — from accident-avoidance systems or, "to the extent widely adopted, the advent of autonomous vehicles" — could materially slow revenue growth [32]. Second, the same filing flags that a reduction in total-loss frequency — for instance from "sharp increases in used car prices that make it less economical" to total a vehicle — would also hit growth [33]. That second risk is not hypothetical: it is exactly what suppressed total-loss frequency during the 2021–22 used-car spike, before the metric recovered above its prior highs [34].
The measured read: the demand engine is intact in direction, and the fiscal-2026 stall is most consistent with a cyclical coverage pullback layered on a growing total-loss pie — the ex-catastrophe declines are moderating, pricing is at records, and total-loss frequency keeps setting year-over-year highs. What tempers that read is pace and duration. The accident-avoidance and autonomy threat is real but slow, gated by how quickly new technology penetrates a roughly 290-million-vehicle U.S. fleet that turns over across a decade or more; it is a multi-year drag, not a near-term one. The nearer question is whether the coverage retrenchment is as cyclical as management says. The read would change on a second consecutive fiscal year of falling ex-catastrophe units, on total-loss frequency rolling over rather than climbing, or on earned car years continuing to fall as premiums stabilize — any of which would move the FY2026 softness from a pause toward a lower-growth regime.
Beyond Insurance
Copart's story is told almost entirely through U.S. insurance salvage, and its growth question has been framed that way throughout this report. Two smaller engines complicate that frame: non-insurance sellers — roughly a quarter of volume — and an International segment now 17% of revenue whose operating income rose about 50% in fiscal 2025. Both held up better than insurance through the fiscal 2026 volume stall. They genuinely support the growth question, not yet large enough to carry it alone.
Copart itself lists five historical growth drivers, and the fifth is "growth in non-insurance company sellers" [1]. The insurance-volume debate (Demand Engine) and the export bid (Export Dependence) both sit inside the U.S. business. This chapter covers what grows outside it.
The three non-insurance engines
Historically about one vehicle in four sold by Copart comes from a seller that is not an insurance carrier, and management has said for several years that this non-insurance volume grows faster than the U.S. insurance business [2]. Management groups it into three parts [3]:
- Blue Car — institutional sellers: banks and finance companies, rental fleets, and corporate fleets. This is the largest and fastest-growing leg, up 15.3% in fiscal 2025 and 20.4% in the fourth quarter of fiscal 2024 [4][5].
- Dealer sales — Copart Dealer Services plus National Powersport Auctions, a wholesale powersport-remarketing platform acquired in fiscal 2017 [6]. Dealer volume grew 1.4% in fiscal 2025 [7].
- Cash For Cars — the consumer-facing channel, where Copart buys a wrecked or unwanted car directly from an individual and resells it on its own account [8]. Liability-only policyholders who total a car and get no insurance settlement are a core supply source.
Two adjacencies sit alongside these. Purple Wave — an online heavy-equipment and agricultural auction house Copart took an 80% stake in for 2.5 million shares in October 2023 — grew gross transaction value 9.4% in fiscal 2025 [9][10]. Low-value units — charities and municipalities — rose 1.2% [11].
Source: FY2025 earnings call, CFO prepared remarks [12].
The mechanism behind the Blue Car growth ties directly to the total-loss-frequency flywheel documented earlier. As total-loss frequency rises, Copart increasingly auctions drivable cars worth five to twenty thousand dollars rather than baskets of parts; that makes it a more natural venue for the whole-car inventory of banks, rental companies and fleets, who then route more vehicles through it [13]. The CEO names this non-insurance liquidity as "lever two" of the growth case, behind the insurance business itself [14]. The same rising total-loss frequency that drives the insurance pool also widens the non-insurance one.
One honest limit on all of this: Copart does not break out how large each leg is. Management has said only that Blue Car, Copart Dealer Services and Cash For Cars are each "substantial" and that it has not disclosed the split [15]. The reader can size the category — about a quarter of volume — but not its parts.
An international segment that changed shape
Copart runs its U.S. and International operations as two reportable segments; International was 17.0% of revenue in fiscal 2025 [16]. It spans eleven countries — the U.K., Germany, Brazil, Canada, the U.A.E., Spain, Finland, Oman, Ireland and Bahrain alongside the U.S. [17]. Over five years its revenue has nearly doubled, from $420M in fiscal 2021 to $792M in fiscal 2025, and its operating income has grown from $113M to $216M [18].
Source: FY2025 Annual Report, Note 14 — Segments and Other Geographic Reporting [19].
The striking figure is the fiscal 2025 operating-income jump — up 49.9%, from $144.0M to $215.8M — on revenue that rose only 2.6% [20]. The gap explains it: the profit growth is a change in mix and margin, not a surge in volume. International unit sales grew 8.1%, but international service (fee) revenue grew 18.9% while purchased-vehicle revenue fell 18.5% [21]. The cause is Germany, where Copart is converting insurance vehicles from a low-margin purchase-and-resell model to the consignment, fee-based model it runs in the U.S. [22]. Low-margin gross revenue drops out and high-margin fee revenue replaces it, so reported revenue barely moves while operating income steps up.
That shows up in segment margins. International's operating margin fell from 26.8% in fiscal 2021 to 17.4% in fiscal 2023, then recovered to 27.3% in fiscal 2025 — back above where it started. Over the same window the U.S. segment margin compressed steadily, from 45.0% to 38.4%.
Source: derived from FY2025 Annual Report, Note 14 segment table [23].
The group-level margin compression this report flagged earlier (Financials and Estimates) is, in segment terms, a U.S. story — the product of fast-growing lower-margin purchase-vehicle volume and heavy facility investment at home. International moved the other way. It remains the lower-margin, smaller half — 12.7% of consolidated operating income against the U.S. segment's 87.3% [24] — but the direction of its margin is improving, and Germany's consignment conversion still has years to run.
International Share of Revenue
International Share of Op. Income
Intl Op. Income Growth FY2025
Non-Insurance Share of Volume
Source: FY2025 Annual Report, Note 14 segment table [25]; non-insurance share per Q1 FY2024 call [26].
How the levers behaved through the fiscal 2026 stall
These engines matter most as a test of what happens when the core business softens. Through fiscal 2026, U.S. insurance volume fell for three straight quarters. In the third quarter, global insurance units were down 2.7% — but global non-insurance units fell only 1.4%, and international service revenue continued to grow at roughly 18%, led by the U.K., Germany and Canada [27][28].
Source: Q3 FY2026 earnings call, CFO prepared remarks [29].
The read is that non-insurance and international are cushions rather than counterweights. They are not immune to the cycle — non-insurance volume declined too — but it declined less, and the fee-led international revenue kept compounding through a quarter in which U.S. units fell 4.2% [30]. That diversification is part of how consolidated revenue held roughly flat while the largest single input went backwards.
What it does and doesn't settle
The measured read: Copart's growth is more diversified than an insurance-only frame suggests, and the non-U.S. and non-insurance pieces are of better and improving quality than their small size implies — an International segment lifting its margin toward the U.S. level as Germany converts to consignment, and a non-insurance channel structurally fed by the same total-loss-frequency trend that drives the core. For the growth half of the case, these are the levers that would need to keep compounding for consensus's high-single-digit forward earnings growth to prove out.
The strongest fact against leaning on them: they are still too small to offset a sustained U.S. insurance decline. The U.S. segment is 83% of revenue and 87% of operating income [31], and U.S. insurance salvage is the bulk of that. Non-insurance is roughly a quarter of volume and it, too, softened in fiscal 2026 [32]. The international profit jump, impressive in percentage terms, rests substantially on a Germany accounting-model conversion that does not repeat indefinitely and lifts a base that is one-eighth of group profit [33].
What would change this read: sustained double-digit Blue Car growth pulling non-insurance toward a third of volume, or international operating income holding above 25% margins after the Germany conversion laps, would turn these into a second growth pillar the valuation does not appear to pay for. The reverse — non-insurance decelerating in step with insurance and international margins slipping back once the German mix shift is complete — would confirm that the case remains, after all, most sensitive to U.S. insurance salvage. The next data point is the fiscal 2026 fourth-quarter and full-year print, where the Blue Car growth rate, the international service-revenue trajectory and the non-insurance unit trend are all disclosed.
Export Dependence
Copart's U.S. ex-catastrophe insurance units fell 7.3%, then 4.8%, then 3.0% across fiscal 2026, yet nine-month revenue held roughly flat because average selling prices rose 4-8% — and that pricing offset rests on international buyers who set about half of U.S. auction value and pay a 38% premium, a demand pool exposed to tariffs, an unhedged dollar and import bans Copart does not control. [1] The revenue arithmetic behind that flat line is laid out in Financials and Estimates; this chapter takes up the demand pool that price rests on.
The 4-8% price gains are what turned 3-7% ex-catastrophe unit declines into roughly flat nine-month revenue, down 0.2%; a sustained give-back in selling prices would turn a flat revenue line into a declining one. That is what makes the valuation in Pessimism Priced In contingent rather than settled: 18.3 times earnings is cheap only if growth and pricing hold, and a declining top line would make 18 times fair, not cheap. The counterweight is that the bid strengthened through the 2022-2026 stretch of tariff escalation and a volatile dollar — the international share of U.S. auction value grew rather than shrank and Copart's gross returns reached an all-time high [2] — so a gradual erosion is a more likely path than a sudden break.
The bid behind the price
The moat and the pricing power documented earlier (Salvage Moat, Demand Engine) both run through one demand pool that Copart's own filings size precisely. In fiscal 2025, vehicles sold to buyers outside the state where the car sat were 69.8% of U.S. units: 31.0% to out-of-state U.S. members and 38.8% to international members, measured by the IP address used during the auction [3]. Management's operational count is a touch higher — international members "account for approximately 40% of all vehicles sold" — and, because those buyers favor more valuable cars, they comprise "almost half of auction proceeds" [4]. The IP-based 38.8% is a conservative floor, since some foreign buyers bid through U.S.-based logistics agents.
Int'l share of U.S. units (FY25)
Int'l share of U.S. auction value
Int'l price premium vs domestic
Registered members
Sources: FY2025 10-K, Item 1 Business [5]; Q4 FY2025 call, Prepared Remarks [6]; Q1 FY2026 call, Prepared Remarks [7].
The premium is specific: in fiscal 2026 the average car bought by an international buyer was "38% higher in value than comparable U.S. buyers," and the share of U.S. auction value going to international buyers "has continued to grow" since 2022 [8]. The reason is freight economics: it is not worth shipping a low-value car across the world, so foreign demand concentrates on higher-end vehicles that can absorb the transport cost [9].
The more important point is how that demand sets price even when it loses. On a given lot, either the international buyer wins — "approximately half of our U.S. auction value is going to an international buyer" — or, failing that, the foreign bidder is often "the push bidder, the second high bidder, which helps to dictate the ultimate sale price" [10]. So the export bid influences a wider slice of proceeds than the roughly half it directly captures. This is the mechanism behind the record selling prices that held revenue flat while units fell: U.S. insurance selling prices grew 5.7% in the fourth quarter of fiscal 2025 alone, at a rate Copart says exceeded the Manheim used-vehicle index and more than fivefold that of comparable service providers [11].
How concentrated the dependence is
The dependence is on a channel, not on any single buyer. Copart has "some 300,000 paying registered members" drawn from "virtually every non-sanctioned country," and the top 10 individual buyers together take only "a low single-digit percentage" of all vehicles sold at U.S. auctions [12]. That fragmentation is a genuine mitigant: no one buyer, and probably no one wholesaler, is load-bearing. The reliance is on aggregate foreign demand for U.S. salvage — and that reliance has deepened over time, with the international unit share rising from 36.4% in fiscal 2022 to 38.8% in fiscal 2025 [13].
What the corpus does not disclose is the geographic split of that channel. Management describes the destinations only in aggregate terms — developing economies seeking affordable mobility — and does not break out volume or value by country. An analyst's recollection that the international mix once sat at "50% to 55%" of value is the closest the transcripts come to a longer history, and management did not contest it [14]. So a reader can be confident the export bid is diversified across many buyers, but cannot rule out that it is concentrated in a handful of corridors — Eastern Europe, West Africa, the Middle East, Mexico — whose fortunes move together with the dollar and with trade policy.
Where the bid is fragile
Copart names the transmission channels itself. The demand pool sits behind three policy and price variables the company does not control.
Sources: FY2025 10-K, Item 1A Risk Factors [15] and FX risk factor [16]; Q4 FY2025 call, Prepared Remarks [17].
On trade policy, the 10-K is explicit that foreign importers "now represent a significant part of our total buyer base," and that laws or treaties restricting the economics of importing vehicles "may reduce the demand for vehicles." It cites a live precedent: a March 2008 Mexican presidential decree that restricted the types of vehicles importable from the U.S. It also flags disputes "over the value assigned to imported vehicles" — the exact lever a customs authority pulls when it wants to tax or slow a flow of used cars [18].
On currency, the exposure the filing names is the translation of Copart's own U.K., Canadian, Brazilian, European and Middle Eastern operations, and it states plainly that the company runs no hedges [19]. The larger currency channel for the export engine is not a separately quantified risk factor but is economically real: foreign buyers earn in local currency and pay in dollars, so a rising dollar directly erodes their purchasing power for U.S. salvage. That is the same "global economic uncertainty" backdrop management referenced when noting the international share kept growing anyway [20].
The chain to earnings is short. A weaker export bid lowers gross returns — the salvage selling price relative to a vehicle's pre-accident value — which lowers the average selling price — the pricing offset that did the most to hold revenue flat against falling units. It would also press on the moat: higher recovery values are what make Copart the preferred outlet for insurers, so a sustained fall in the export bid would loosen that tie at the same time it cuts fee revenue.
What the recent record shows
The evidence to date cuts against reading this as an imminent problem. Through 2022 to 2026 — a period of escalating tariffs and a volatile dollar — the international share of auction value grew rather than shrank, unique bidders per auction reached all-time highs, and Copart's gross returns hit a high-water mark [21]. A fragmented, 300,000-member buyer base spanning many countries has absorbed those shocks without a visible dent in pricing [22].
The measured read: the export bid is a strength that has proven resilient, but the flat-revenue story is most sensitive to it, and it is the input here that Copart controls least. The dependence is diversified across buyers and years, which makes a gradual erosion far more likely than a sudden break. The read would change on a clustered shock — a sharp dollar spike alongside tariff or import-ban actions in more than one large corridor — that pulled average selling prices down while insurance units were still soft, turning a flat revenue line into a declining one. The falsifiable signposts are on the tape every quarter: U.S. insurance selling prices against the Manheim index, gross returns, and the international share of auction value. A sustained fall in selling prices while units stay weak would be the first sign the bid behind the price is thinning.
Pessimism Priced In
Copart trades at $29.12, about 18 times earnings and, with $4.2 billion of net cash stripped out, roughly 13.5 times operating profit — the cheapest the stock has been in a decade after a 54% fall from its May 2025 peak. At that multiple the market embeds roughly 3–4% perpetual earnings growth against a business that compounded net income at ~12.5% over three years and that consensus still models re-accelerating to ~7% after a fiscal-2026 trough. The de-rating has priced in a permanent step-down; whether that is right is most sensitive to the volume question Demand Engine leaves open.
Share Price
P/E (trailing)
EV / EBIT
FCF Yield (FY26E)
Net Cash / Share
Sources: price and consensus per market data as of Aug 2026; multiples derived from the FY2025 10-K income statement and balance sheet [1] and the Q3 FY2026 10-Q balance sheet [2].
The de-rating in one picture
At the May 2025 peak of $63.84, Copart fetched about 40 times its fiscal-2025 diluted earnings of $1.59 — the kind of premium multiple the stock had carried for most of the prior decade [3]. At $29.12 it fetches 18.3 times. Because $4.2 billion of the market value is net cash — cash, restricted cash and held-to-maturity Treasuries with no offsetting debt [4] — the operating business alone changes hands at about 15.5 times earnings and 13.5 times operating profit.
Source: $63.84 peak (May 16, 2025) and $29.12 (Jul 31, 2026) per market data; earnings and net cash per the FY2025 10-K [5] and Q3 FY2026 10-Q [6].
The market pays P/E for a stable earner, but this is a business sitting on a cash pile worth 16% of its share price and carrying no debt, so the enterprise-value lens matters more than the headline multiple. On fiscal-2026 consensus, enterprise value of about $22.8 billion is 13.5 times operating profit of roughly $1.69 billion and 11.9 times EBITDA of roughly $1.92 billion. A capital-light auction franchise earning a 36% operating margin at 12 times EBITDA is not a demanding price by its own history.
What the multiple implies
The cleanest way to read the multiple is to invert it. A stock priced at 18.3 times earnings carries an earnings yield of 5.4%. For a company that converts most of its profit to cash, a 9% required return implies the market is paying for about 3.6% perpetual earnings growth; on the ex-cash operating business at 15.5 times, the embedded growth is nearer 2.6%. Both sit far below what Copart has delivered and what the Street projects.
Source: embedded growth derived from the current multiple at a 9% discount rate; consensus EPS path per consensus estimates; realized net-income CAGR per the FY2025 10-K three-year income statement [7].
As arithmetic, the gap is the 3–4% growth embedded in the price against the ~7% consensus builds in and the ~12.5% Copart realized over three years. If Copart's growth has permanently downshifted to the low single digits — the outcome a structural read of the fiscal-2026 volume stall would produce — then 18 times is a fair price, not a cheap one. If growth reverts toward the ~7% consensus builds in for fiscal-2027 onward, still less than half its historical mid-teens pace, the current multiple understates the business. The de-rating has already resolved that debate in the bear's favour; the evidence in the Demand Engine chapter — a secular total-loss-frequency tailwind intact while the near-term unit softness moderated from -7.3% to -3.0% through the year — points the other way, but has not yet shown up in the numbers.
The forward earnings path consensus sees
Consensus does not model decline; it models a one-year pause. Diluted EPS holds essentially flat at $1.58 in fiscal-2026 — despite net income falling about 2.5% to roughly $1.51 billion, because the fiscal-2026 buyback cut the share count by 4.3% [8] — then rebuilds to about $1.97 by fiscal-2029, a ~7.4% annual pace off the trough.
Source: FY2025 actual per the FY2025 10-K [9]; FY2026E–FY2029E per consensus estimates (13 analysts near-term, thinning to 2 by FY2029).
Two cautions sit inside that curve. Consensus extends only about two years with conviction — the FY2029 figure rests on a handful of analysts, and Copart gives no formal long-range guidance, so the compounding case cannot be anchored to a reliable multi-year estimate. And a slice of recent profit growth was interest on the cash pile — $178.9 million, about 9% of pre-tax income in fiscal-2025 [10] — which fades as the company spends that cash on its own shares.
From price to value: the scenarios
Holding the fiscal-2029 consensus EPS of $1.97 and varying only the exit multiple frames the return. A permanent low-growth regime (15x) leaves the stock roughly where it trades today; the current multiple held (18x) delivers a mid-single-digit annual return on price alone; a partial re-rating toward Copart's historical band (22–25x) reaches the sell-side's mean target and beyond. To each, add a starting free-cash-flow yield near 5% and continued share shrinkage.
Source: exit multiples applied to FY2029E consensus EPS of $1.965; upside measured against the $29.12 close, excluding dividends/buyback accretion. Derived from consensus estimates.
The sell-side lands in the middle of this: a mean target of $40.30 and median of $41.00 imply about 22–25 times fiscal-2026 earnings, roughly +38% from the current price — a partial return toward the historical multiple rather than a round-trip to the peak. The distribution is skewed upward, and the most bearish target sets a shallow floor.
Source: consensus analyst price targets (10 estimates) and the $29.12 close, per market data as of Aug 2026.
Notably, the lowest target on the Street — $26.00 — sits only about 11% below the current price, while the high is $55.00. Ten analysts split 2 strong-buy, 5 buy, 5 hold and 1 strong-sell. The debate is real, but even the bear anchor implies a modest drawdown, not a rout.
The margin of safety, and the "expensive stock" question
For a value investor, the downside math is as important as the upside. About $4.54 per share — 16% of the price — is net cash with no debt against it, and another $3.89 per share is owned salvage-yard real estate carried at $3.6 billion [11]. Together, liquid assets and owned land account for roughly 29% of the share price before any value is assigned to the auction franchise itself. Combined with the debt-free balance sheet detailed in Capital and Control, the probability of permanent capital loss from solvency risk is close to nil — the specific comfort this reader requires.
That reframes an exclusion. For most of its life Copart was exactly the kind of name a margin-of-safety investor avoids: a beloved compounder at 30–40 times earnings, priced for perfection. Judged only on the arithmetic today — 18 times headline, 15.5 times ex-cash, 13.5 times operating profit, on a business earning 36% margins with net cash — the "expensive" label no longer fits. The stock now trades at roughly a market multiple for a franchise of clearly above-market quality. The honest counter is that 18 times is only cheap if growth resumes; if the volume stall proves structural and earnings settle into low-single-digit growth, the multiple is fair and the margin of safety is the balance sheet, not the price. The value case does not rest on the multiple alone — it rests on the demand read being cyclical.
The valuation is most sensitive to one assumption: whether forward earnings growth reverts toward the ~7% consensus builds in, or settles at the ~3–4% the multiple embeds. At $29.12 the market has chosen the lower path. What would change the read is a return to positive ex-catastrophe insurance unit volumes — the falsifiable line to watch, quarter by quarter.
Source: sensitivity framing derived from consensus estimates and the reverse-earnings-yield calculation above.
Bull and Bear
Most facts in the Copart case are settled: about $4.2 billion of net cash and no debt [1], a 36.5% operating margin roughly double its nearest rival's [2], a rising total-loss-frequency tailwind. The dispute is narrower: whether the fiscal-2026 insurance-volume stall is a cyclical trough or a structural step-down, and whether the record prices holding revenue together rest on demand Copart controls. This chapter lays the shared facts side by side and names what would settle each.
Where the two cases diverge
The case is most sensitive to one variable — the direction of insurance unit volume. U.S. insurance units excluding catastrophe effects fell 7.3% in the first quarter of fiscal 2026, then 4.8%, then 3.0% — a decline that is real but has moderated each quarter [3][4][5].
Source: Q1–Q3 FY2026 earnings call transcripts [6][7][8].
The bull reads the moderating slope as a cyclical trough: premium-squeezed households have shed collision coverage — earned car years fell 4% year-over-year against a vehicle fleet that grew 1.4%, and 25% of repairs are now self-pay — while total-loss frequency kept climbing to 23.6% in the first calendar quarter of 2026, from 15.6% a decade earlier [9][10]. The bear notes that the "cyclical" label is management's own, that the softness has run about two years with no dated end, and that the fiscal-2025 10-K itself flags accident-avoidance systems and, eventually, autonomous vehicles as able to materially reduce accident rates, with sharp used-car-price increases capable of suppressing total-loss frequency as they did in 2021–22 [11]. The evidence that settles it is narrow: whether ex-catastrophe units cross back to positive, or a second full fiscal year prints negative.
The second disagreement is about what held revenue flat while units fell. U.S. insurance average selling prices set records — up 8.4% in the first quarter and 4.1% in the third, beating the Manheim used-vehicle index — so fee revenue per unit rose enough to offset the volume decline [12][13]. That pricing rests heavily on international buyers, who take close to half of U.S. auction value, pay about 38% more per vehicle than domestic buyers, and often set the price as the second-high "push" bidder even when they lose (Export Dependence) [14][15]. The bull observes that this bid strengthened through the 2022–2026 tariff-and-dollar turbulence rather than weakening; the bear observes that it is exposed to tariffs, an unhedged dollar, and import bans that Copart does not control.
The tension table
Each row is a fact both sides accept; the disagreement is the interpretation, and the last column is the evidence that resolves it.
Two rows carry the report's weight, each with a canonical statement worth stating plainly. On the structural volume pool (row 3): U.S. total-loss frequency has climbed from 15.6% of claims in 2015 to 23.1% in 2025, and the same perimeter-mounted safety sensors that gradually reduce accidents raise repair costs enough that rising total-loss frequency more than offsets the accident-frequency decline.[16] On the pricing that held revenue together as volume fell (row 5): Copart's U.S. ex-catastrophe insurance units fell 7.3%, then 4.8%, then 3.0% across fiscal 2026, yet nine-month revenue held roughly flat because average selling prices rose 4-8% — and that pricing offset rests on international buyers who set about half of U.S. auction value and pay a 38% premium, a demand pool exposed to tariffs, an unhedged dollar and import bans Copart does not control.[17][18][19][20][21]
Sources: Q3 FY2026 10-Q, Consolidated Balance Sheets and Note 6 — Stock Repurchases [22][23]; FY2025 10-K income statement and risk factors [24][25]; RB Global FY2024 income statement [26]; FY2026 earnings call transcripts [27][28]; valuation arithmetic in Pessimism Priced In.
The rows are not equally weighted. Rows 1 through 3 favor the bull and are the most settled: the balance sheet is audited, the margin gap is two companies' filed statements (Salvage Moat), and the decade-long total-loss-frequency climb is the structural pool the whole business feeds on (Demand Engine). Rows 4 through 7 are where the case is genuinely undecided, and they share a root: whether growth reverts. If ex-catastrophe volume inflects and the export bid holds the record ASPs, the flat fiscal-2026 earnings line is a pause and the ~7.4% consensus path is credible; if units keep sliding, 18.3x is a fair multiple for a business that has stepped down, and consensus — thin beyond two years, with no company guidance to anchor it — is the assumption at risk.
What to watch
The disagreements are falsifiable. Each signpost below is a specific line in a specific filing, with the threshold that moves the read. The next data point is the fourth-quarter and full-year fiscal-2026 result, scheduled for September 3, 2026.
Sources: signposts drawn from FY2026 earnings call transcripts and the Q3 FY2026 10-Q [29][30]; next scheduled report September 3, 2026, per consensus calendar.
The evidence does not force a winner, and the honest close is to say so. The quality half of the case — the $4.2B of net cash and no debt, the ~19-point margin gap, the rising total-loss-frequency pool, the founders' capital now flowing to buybacks — is well supported and largely settled. The growth half turns on the ex-catastrophe volume trajectory and the durability of the export-driven pricing that has masked it, neither of which the corpus can resolve ahead of the prints. That is the reconciliation: a durable, cash-backed franchise trading at a market multiple, where the gap between a compounder-at-a-discount and a fairly-priced slower grower is a small set of quarterly numbers a reader can watch converge.